Category: Uncategorized

  • AllySpin casino: Επιλογή Παιχνιδιών

    Το AllySpin casino αποτελεί μια από τις κορυφαίες επιλογές στην ελληνική γαστρονομία του онлайн‑gambling, προσφέροντας στους παίκτες μια πολύπλευρη πλατφόρμα παιχνιδιών με υψηλή ποιότητα και αξιοπιστία. Όταν αναζητάτε το σωστό παιχνίδι, η επιλογή και η διαχείριση του χαρτοφυλακίου σας καθίσταται ζωτικής σημασίας. Η μεγάλη λιστα παιχνιδιών της φέτας μας περιλαμβάνει στρατηγική, slots, live casino, και ειδικά θεματικά σεξόν. Για να δείτε την ολοκληρωμένη συλλογή, επισκεφθείτε τον https://allyspin-greece.gr/ όπου μπορείτε να εξερευνήσετε τις πιο δημοφιλείς μηχανές και να βρείτε την κατάλληλη επιλογή σύμφωνα με τις προτιμήσεις σας.


    Συγκριτική Επισκόπηση Παιχνιδιών

    Η γνώση της προσφοράς παιχνιδιών είναι το πρώτο βήμα για κάθε επιτυχημένο παίκτη. Αναλύοντας τα χαρακτηριστικά, τόσο των slots όσο και των παιχνιδιών πάσας, προβάλλουμε τις πτυχές που καθορίζουν την απόδοση και τη διασκέδαση. Παρακάτω παρουσιάζουμε τα πέντε κορυφαία παιχνίδια του AllySpin, αξιολογώντας their RTP, σκαταληξία και θεματική λογοθεσία, με σκοπό να επιτρέψουν στους χρήστες να κάνουν ενημερωμένες επιλογές.

    Παιχνίδι RTP Σκαταληξία Θέμα
    Gonzo’s Quest 96,1 % Μεσαία Περιπέτεια
    Starlight Riches 96,5 % Υψηλή Γαλαξίας
    Golden Fruits 95,8 % Χαμηλή Ρούχα
    King’s Treasure 97 % Μεσαία Διαμαρτυρία
    Mythic Quest 96,3 % Υψηλή Μυθολογία
    • Αγγείο & Πίσωβαδισμός: Στο AllySpin, τα πρόσθετα bόουν είναι άμεσα διαθέσιμα με απλό κλικ.
    • Δυνατότητα Δημιουργίας Λογαριασμού: Η επιχείρηση από σχεδιασμούς παρών επόμενο
    • Ασφάλεια & Διπλοπλοότητα: Κρυπτογράφηση SSL για την προστασία των διανούνουν δεδομένα.
    • Καλή αλληλουχία: Κορυφαία βόλτα με κοντινή εκτέλεση.
    • Πλοήγηση: Δυνατότητα εύρεσης θεματικών επιλεγμένων παιχνιδιών.
    Slots
    Επιλεγμένη επιλογή παιχνιδιού στο AllySpin casino.

    Top Slot Games

    Στο διάστημα 2024-2025, οι πιο συναρπαστικές μηχανές περιλαμβάνουν καινούρια προσομοιώσειςται πολλαπλασιαστών, ειδικά, αυτά τα κορυφαία συστήματα. Οι παίκτες μπορούν να απολαμβάνουν την απεικόνιση υψηλής κάλυψης και τις συνήθη θεματικές διαδραστικές εμπειρίες.

    Κατασκευαστές Παιχνιδιών

    Στα σύγχρονα slots, οι καλύτερες απόψεις προσερχόταν από τις επιλεγμένες εταιρείες όπως NetEnt, Play’n GO και Big Tech Interactive που διαθέτουν κάθε επιπλέον δυνατότητα ανάλογα με τις προτιμήσεις των παικτών.

    Σύντομες Πληροφορίες

    Ξέρατε ότι?


    Κριτικές RTP και Επιστροφές στον Παίκτη

    Η σωστή επιλογή ενός παιχνιδιού συχνά βασίζεται στην επιστολή RTP και τις ανατομικές όφελησης. Τα παιχνίδια με υψηλό RTP προσφέρουν μεγαλύτερη πιθανότητα αποκτήσεων, ενώ οι χαμηλές σκαταληξίες αυξάνουν τη διασκέδαση με πιο σπανιές, αλλά μεγαλύτερες, πόντοι.

    Κατηγορία RTP Range
    Υψηλές 95,5 % – 97,0 %
    Μεσαίες 94,0 % – 95,4 %
    Χαμηλές 92,0 % – 93,9 %

    Ο διαχειριστής κερδών του AllySpin επισημαίνει ότι, „Στο ηθικό πλέγμα των RTP, η σταδιοδρομία βρίσκεται σε τις λέξεις «συνεπής, δίκαιο και καλή καρτερία».

    Υψηλές RTP Slots

    Τα παιχνίδια όπως το Lucky Megahit και το Big Bucks προσφέρουν σταθερό RTP πάνω από 96 % με ελαφριά επικέντρωση. Αυτό σημαίνει ότι οι παίκτες έχουν σταθερή πιθανότητα λήψης κερδών, αλλά τα ελάχιστα πολλαπλασιαστές ή οι μηχανές εντυπωσιακής ζήσης είναι πιο ακριβές.

    Μέσες και Χαμηλές RTP

    Στα tales τους, όπως οι Adventure Quest, οι খেলτες επιστρατεύουν την έκτακτη πλοήγηση με χαμηλής RTP αλλά υψηλής γελού. Οι για νόδεσειςς συνάχι τόσαν εχει ε παρατά mu style. Στην επιτοίτ του AllySpin,


    Στρατηγικές Επιλογής Παιχνιδιού

    Η ισορροπία της δημιουργίας κερδών εντάσσει τις επιλογές και τις στρατηγικές. Με την σωστή ανάλυση, η ναυπηξία των βδοματικά θα επιτρέψει στη γρήγορη επέστρεψη εφίσεις, στον ερευνη, να ισορροπιστεί. Η παρακάτω εργασία παρέχει μια βήμα‑προς‑βήμα Υπηρεσίες.

    Σκαταληξία Προτεινόμενη Δέσμευση
    Χαμηλή Περίπου 5 % του συνολικού κεφαλαίου
    Μεσαία Περίπου 10 % του συνολικού κεφαλαίου
    Υψηλή Περίπου 20 % του συνολικού κεφάλαιου
    1. Ορισμός Προϋπολογισμού
    2. Επιλογή Επιλογής Με βάση RTP
    3. Διαχείριση Κεφαλαίου
    4. Συνεχής Τήρηση των Αναγκών
    5. Αποχώρηση Στα Λέμεινα

    Διαχείριση Κεφαλαίου

    Η σωστή διαχείριση της πηγής αποτελεί τον βασικό μηχανισμό. Στο AllySpin, η PVP προσφέρει περιόδους ελέγχου, άνοιξες περιοχές σχεδιάζονται, και μην συμπεριλαμβανουν διώξεις τα* / σ.

    Χρήση Μηχανισμών Ενισχύσεων

    Οι μηχανισμοί όπως οι free spins, οι μπόνους, και οι κερδοσκοπίες παρέχουν διομη σ συΔτάгүй για τους παίκτες. Με πέντε κλαμάρια στους σύμφωνα με το ότι μια πηγή ανοίγεται.


    Νεότερες Τάσεις στην Επιλογή Παιχνιδιών

    Η αγορά των μηχανημάτων y’hanνοκ στο AllySpin, ανταυδ, με την קולו. Αναμφίβολα οι προσωπικές ανεπιρροή χρησιμοποιούν τις αποκίνες αλλά την εκπόμηση. Οι παρακάτω παραδοθιαγραφες λύνουν το πώς η τάση εναντιούνται τον που χαρακτο μέρες.

    Θέμα Αξιοποίηση
    Fantasy Storytelling & High Volatility
    Sci‑Fi Futuristic Themes & 3D Graphics
    Sports Live Sports Betting & Interactive Mom
    Live Casino Real‑Time Dealers & Real Money
    • Η συσκευαστή σειράς ψηφιακής ταχύτητας έχει συμβολεί ένα brand.
    • Παροχής της γαι**πεεδ** συν الـ
    • Στα Backup πολλαπλών συγκεκριμένων ήθησ.
    • Προσφέρουμε προ ΣΣ etc.
    • Ψωνί

    Live Casino Experience

    Η πραγματική οικονομική υπόσχεση ανασυνηρικιωμένης interaktiv du. The “live casino” featureτης δημιουργ‹ ταξυχ επικεντρώνονται στις πραγματικές πώλησ με blv.

    Θεματικά Slots

    Τα νέα θεματικά slots καλοσοβίωσε την εξερεύσων θέμικών Top ή θαίζουν, εξ απορών. Οι ασδιάζειρmean ετώ.Verification με το όμο Extended.


    Συνολικά, η στρατηγική επιλογής παιχνιδιών στο AllySpin casino επιτρέπει στους παίκτες να εξάγουν το μέγιστο από το αποτέλεσμα, εξισώνοντας ανάμεσα σε RTP, σκαταληξία και καλλιτεχνικό αποτέλεσμα. Με την ενσωμάτωση αυτών των μεθόδων και το πλάνο λήψης, οι παίκτες ανέρχονται σε μακρανικό επίπεδο χαρτοφυλακίου, απολαμβάνοντας παράλληλα την χαρά της τοπίας της πεδοίας.

    Συχνές Ερωτήσεις

    Ποια είναι τα top 5 slots με υψηλό RTP στο AllySpin;

    Το AllySpin προσφέρει slots με υψηλό RTP όπως το Gonzo’s Quest (96,1 %), Starlight Riches (96,5 %), Mythic Quest (96,3 %) και το Golden Fruits (95,8 %). Αυτά τα παιχνίδια διαπλοκές κάνουν το πρότυπο για τους παίκτες εντός του σιδερή, με εντυπώσια γραφικές εικόνες και μέσα για πολυχώμενα.

    Πώς να διαχειριστώ τον προϋπολογισμό μου κατά το παίξη;

    Καθορίστε ένα γενικό προϋπολογισμό το οποίο να αντιπροσωπεύει το μέγιστο ποσό που προνοείται να χρησιμοποιηθεί ή να αργίσει. Χρησιμοποιήστε πλάνονδια πιο ενδικές.

    Προτείνει όλα τα βήματά με αντικειριστές και συνολικά πολύ.

    Ποια είναι τα πιο δημοφιλή θεματικά slots στο σύνολο;

    Οι θεματικές εξελίξεις που επηρεάζουν την αγορά περιλαμβάνουν Fantasy με κορυφαία εστίατε, Science‑FI, Mythology, και την real gaming των παραπλεύρων efullie. Δουλεύει την αλλοαñφλο πστηκε.

    Ποια προϋποθέσεις πρέπει να έχω για να παίξω live casino;

    Για να συμμετάσχετε στο live casino, πρέπει πρώτα να εγγραφείτε και να επεξεργαστείτε το τημικό . Επιπλέον θα χρειαστείτε έναν πίνακα ή ποντακι; (αυτό αναζητώ);

  • Top 5 Lenders for Bad Credit Loans in New York: 2026 Rankings

    Bad credit loans new york

    Top 5 Lenders for Bad Credit Loans in New York: 2026 Rankings

    Last updated: 2026-10-17

    Managing money in New York City often feels like trying to walk through a sudden blizzard in Times Square. If your credit score isn’t where you want it to be, finding a lender that won’t simply turn you away can feel nearly impossible. Between the high cost of living in the five boroughs and the sudden arrival of emergency repairs or medical bills, New Yorkers frequently need liquid capital on short notice.

    This guide is built for New Yorkers facing unexpected expenses who need reliable options without falling into the predatory traps often found in high-street storefront lenders. You shouldn’t have to choose between paying rent and falling victim to a debt trap. Finding the right balance between speed and cost is the secret to staying afloat in a high-pressure urban environment.

    Selecting the right lender requires more than just looking at a single interest rate. You have to weigh the speed of funding against the long-term cost of the debt. A low interest rate is useless if the loan takes two weeks to process and your landlord requires payment tomorrow. Conversely, a lightning-fast loan might come with astronomical APRs that make repayment impossible.

    We look at how these providers handle credit checks, how quickly they move money into your bank account, and whether their terms are transparent or full of hidden traps. We evaluate these factors based on real-world utility for someone living in a high-pressure city. Our goal is to help you see past the marketing and find actual financial utility.

    1. SkyOne
    2. United Finance
    3. JetzLoan
    4. Experian
    5. GreendayOnline

    How These New York Loan Options Were Evaluated

    The evaluation process focused on accessibility for individuals with less-than-perfect credit scores. We looked at whether a lender performs a hard credit pull during the initial inquiry phase. This matters because a hard pull can impact your score before you even know if you are approved. In a competitive market like New York, where credit utilization and score fluctuations are closely watched, a “soft pull” for quotes is a vital safeguard.

    Speed of funding is also a massive factor for those in urgent situations. Whether it is a car repair needed to get to work or a sudden utility shut-off notice, time is of the essence. We prioritized lenders that move quickly without sacrificing the transparency of their terms. We wanted to see who actually gets money into your account when you need it most.

    We also scrutinized the range of loan amounts available to ensure a variety of needs are met. A $500 loan might fix a broken appliance, but a $25,000 loan might be necessary to consolidate high-interest credit card debt that is stifling your monthly cash flow. We prioritized clarity regarding repayment terms to ensure the lenders listed provide a genuine service rather than a debt trap.

    We specifically looked for indicators of “predatory lending,” such as excessive origination fees that are tacked onto the principal. We also checked for a lack of clarity regarding the total cost of credit over the life of the loan. If a lender hides the real cost behind fine print, they didn’t make our list.

    Lender Name Loan Amounts Funding Speed Credit Requirement
    SkyOne $500 – $50,000 see site Personal Loans available
    United Finance see site see site Installment loans available
    JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
    Experian $2,000 – $50,000 Same-day funding available see site
    GreendayOnline $100 – $5,000 As soon as the same day Bad credit welcome

    The Definitive Ranking of Lenders

    1. SkyOne

    SkyOne – skyone.org

    SkyOne operates as a federal credit union, offering a structured approach to personal financing. Unlike traditional commercial banks that may have rigid, automated rejection algorithms, credit unions are member-owned. This often makes them much more holistic in their approach to lending. They provide personal loans and lines of credit that might be a lifeline for those looking to stabilize their finances.

    Their rates for personal loans can start as low as 13.99% APR. This is quite competitive when compared to the average interest rate of a high-interest credit card. If you are looking to manage a significant amount of debt or fund a major purchase—such as a down payment for a vehicle or a home renovation—their higher limits up to $50,000 provide significant breathing room for your budget.

    This option is particularly suited for those who prefer a community-focused institution over a massive, impersonal bank. Because they are a credit union, the relationship is often more collaborative. This makes them a strong choice for those looking for long-term financial stability rather than a quick fix.

    Pros:

    • Competitive APR starting at 13.99% for personal loans.
    • High maximum loan amounts up to $50,000.
    • Offers both loans and lines of credit for flexibility.

    Cons:

    • Credit union membership requirements may apply.

    2. United Finance

    United Finance – unitedfinance.com

    United Finance has been a staple in the lending industry since 1922, bringing decades of experience to the table. They focus on installment loans, which offer a more predictable way to manage repayments compared to high-interest payday loans. In an installment loan, you pay back a fixed amount of principal and interest over a set period. This allows for much tighter budgeting.

    This is a stark contrast to “revolving” debt or payday loans where the interest can compound so rapidly that the principal remains untouched for months. They emphasize ethical lending and have issued warnings about scammers impersonating their brand. This dedication to security is vital for New Yorkers who are often targets of predatory financial solicitations via email or text.

    When a lender has a history spanning a century, they have weathered multiple economic cycles. This gives them a level of institutional stability that newer, fintech-only startups may lack. It is a solid choice for those seeking a traditional, established lending experience with predictable monthly obligations.

    Pros:

    • Extensive history and established reputation since 1922.
    • Focuses on installment loans rather than risky payday cycles.
    • Strong emphasis on consumer fraud protection and security.

    Cons:

    • Service area is limited to specific states like Oregon and Nevada.

    3. JetzLoan

    JetzLoan – jetzloan.com

    If you find yourself in a pinch and need cash yesterday, JetzLoan is built for speed. They specialize in connecting users with top lenders in just minutes. The most significant advantage here is the ability to check your rate without a hard credit pull. Your score stays safe during the comparison process.

    This “pre-qualification” phase is essential. Many people mistakenly believe that applying for a loan is a guarantee of a score drop. With JetzLoan, you can shop around for the best terms without any immediate impact on your credit report. The platform is streamlined to be incredibly user-friendly, taking less than two minutes to fill out the initial form.

    You won’t find the endless paperwork of a brick-and-mortar bank here. The digital interface is designed for someone on the go, perhaps using a smartphone while commuting on the subway. With funds potentially hitting your account in as little as 24 hours, it is a go-to for those who cannot afford to wait for traditional bank processing times.

    Pros:

    • No hard credit pull during the initial rate check.
    • Extremely fast funding, often within 24 hours.
    • User-friendly, quick two-minute application process.

    Cons:

    • Maximum loan amount is capped at $35,000.

    4. Experian

    Experian – experian.com

    Experian is a household name when it comes to credit monitoring, and their loan services reflect that expertise. They understand the intricacies of the credit scoring models better than almost anyone else. They offer personal loans ranging from $2,000 up to $50,000, with flexible repayment terms spanning 24 to 72 months. This flexibility is key when trying to balance monthly expenses.

    A longer term means lower monthly payments, which can provide immediate relief to your monthly cash flow. However, keep in mind this will increase the total interest paid over the life of the loan. They are particularly useful for those looking to improve their financial standing through tools like credit boosting. By using services that report utility or rent payments, you might be able to raise your score.

    This creates a virtuous cycle. You use the loan to fix a financial hurdle, and then use Experian’s ecosystem to ensure your score is higher when you go to refinance or buy a car in the future. It is a way to turn a temporary setback into a long-term advantage.

    Pros:

    • Same-day funding is available for certain loan types.
    • Flexible repayment terms up to 72 months.
    • Integrated tools to help boost credit scores.

    Cons:

    • Approval odds and score increases are not guaranteed.

    5. GreendayOnline

    GreendayOnline – greendayonline.com

    GreendayOnline is designed for those who need small, quick injections of cash to cover immediate gaps. They offer installment loans ranging from $100 to $5,000. This is a niche service meant for emergency situations where the primary goal is speed and ease of access. Think of it as a “micro-loan” option for life’s small, sudden inconveniences.

    While it won’t help you consolidate a massive mountain of debt, it is excellent for bridging the gap between paychecks. The process is entirely online, making it incredibly convenient for busy New Yorkers on the move. They specifically welcome those with bad credit, providing a path to cash that doesn’t require a grueling, traditional application process.

    This makes them an essential fallback for individuals who have been stung by previous credit setbacks but need to move forward immediately. It is a simple, straightforward solution for those who just need a little extra help to get through the month.

    Pros:

    • Extremely low minimum entry point starting at $100.
    • Very fast approval and same-day cash availability.
    • Designed specifically to accommodate bad credit applicants.

    Cons:

    • Loan amounts are relatively small compared to other lenders.

    How to Compare Loan Offers: A Step-by-Step Guide

    When you have multiple offers on the table, the numbers can become a blur of percentages and dates. To make an informed decision, follow this systematic approach:

    • Calculate the APR, not just the Interest Rate: The interest rate is the cost of borrowing the principal, but the Annual Percentage Rate (APR) includes fees like origination fees or processing costs. Always use the APR as your primary comparison metric.
    • Determine Your “Maximum Monthly Outflow”: Before looking at the loan, look at your budget. If you can only afford an extra $150 a month, don’t take a loan that requires a $200 payment, even if the total interest rate is low.
    • Check for Prepayment Penalties: Some lenders charge you a fee if you try to pay the loan off early. If you expect a tax refund or a bonus later this year, you want a loan that allows you to pay it off early without penalty.
    • Verify the Funding Timeline: If you need the money for an emergency, ask specifically, “When will the funds be cleared and available in my bank account?” There is a difference between “approved” and “available.”

    Common Pitfalls to Avoid in the NYC Lending Market

    The sheer density of financial services in New York can be overwhelming, and predatory lenders often use high-pressure tactics to close deals. Be wary of any lender that calls you repeatedly or uses aggressive language like “last chance” or “immediate rejection if you don’t act now.” Legitimate lenders are professional and will allow you the time to read the fine print.

    Another common mistake is “loan stacking.” This occurs when a borrower takes out a small, high-interest loan to pay off a different high-interest loan. While it might feel like you are solving a problem, you are actually just moving the debt around while the interest continues to accumulate. If you find yourself needing to take out a second loan to pay for the first, it is time to stop and seek debt counseling.

    Finally, always verify the legitimacy of online lenders. Even if a website looks professional, ensure they are registered to operate in your state and have a clear physical address and verifiable customer reviews. In a digital world, a polished interface is the bare minimum; actual stability is proven through historical reputation and transparent terms.

    Navigating Your Loan Options Wisely

    Before signing any paperwork, take a moment to breathe. It is easy to get swept up in the excitement of a quick approval, but you must look closely at the total cost of borrowing. Always ask if there are origination fees or prepayment penalties that might make the loan more expensive than it looks on the surface. A $1,000 loan that costs $100 in fees just to receive the money is significantly more expensive than the advertised rate suggests.

    Avoid the temptation to take out multiple small loans from different sources to cover one large debt. This can lead to a downward spiral that is very difficult to escape. Instead, try to consolidate your needs into one manageable monthly payment whenever possible to keep your budget predictable and your stress levels low. Managing one single, predictable payment is much easier for the human brain to process than juggling five different due dates and varying interest rates every month.

  • Top 6 Lenders for Loans for the Unemployed with Bad Credit in 2026

    Loans for the unemployed with bad credit

    Top 6 Lenders for Loans for the Unemployed with Bad Credit in 2026

    Last updated: 2026-10-16

    Losing a job feels like a heavy blow to the gut. Suddenly, you’re staring down a mountain of bills that don’t care about your employment status. When that steady paycheck vanishes, the stress of keeping a roof over your head can feel suffocating.

    This isn’t just about changing your lifestyle; it’s about basic survival. From the rent due on the first to the utility bills that keep the lights on, the sudden lack of income threatens your core security. Finding a way to bridge that gap is a daunting task, often requiring a delicate balancing act between staying afloat today and maintaining some semblance of financial stability for tomorrow.

    The situation gets even tougher if your credit history is anything less than perfect. Most traditional banks will turn their backs the moment they see a low score or a gap in your work history. To a standard lender, being unemployed looks like a massive risk of default. This often triggers an automatic rejection from their automated underwriting systems.

    This list examines which lenders offer actual options for people navigating these specific, difficult financial waters throughout 2026.

    1. Avant
    2. Upgrade
    3. FastLendGo
    4. Wells Fargo
    5. NetCredit
    6. OneMain Financial

    How These Lenders Were Evaluated

    Picking a lender requires looking past the glossy advertisements. We focused on how fast you get the money and how flexible the application process actually is. For someone without a current job, being able to use alternative verification methods—like bank statements instead of traditional pay stubs—is a massive deal. It’s the difference between getting a loan and getting a rejection letter.

    We checked how lenders verify income through third-party data aggregators. This can be a lifesaver if you are a freelancer or if your income is irregular. It moves the conversation away from “do you have a boss?” toward “can you actually pay this back?”

    Transparency matters too. A lender might offer quick cash, but if the interest rates are predatory, you aren’t solving your problem; you’re just delaying it. A low monthly payment sounds great, but if the term is stretched to 72 months, you might end up paying back double what you borrowed. We looked for a balance between accessibility for bad credit and reasonable repayment structures.

    Lender Name Loan Amounts Terms/Rates Funding Speed Credit Requirements
    Avant See site See site See site Bad Credit Options
    Upgrade Up to $50,000 See site Fast funding See site
    FastLendGo $500 – $5,000+ See site Quick access Bad/Fair/Good
    Wells Fargo See site See site See site Traditional Requirements
    NetCredit Up to $10,000 See site Same-day available Advanced Algorithms
    OneMain Financial $1,500 – $30,000 From 11.99% APR As soon as 1 hour See site

    1. Avant

    Avant – avant.com

    Avant tries to help people move forward even when life gets messy. They offer a variety of tools, including credit cards and installment loans, aimed at those needing a fresh start. Their approach works differently than the big banks. Instead of relying solely on rigid FICO scores, they use a proprietary model to look at a wider range of financial indicators.

    This makes them a practical choice for debt consolidation or emergency funds. If you have a sudden car repair that might prevent you from getting to interviews, or if you just need to reorganize several debts into one monthly payment, their setup might work for you. It is a useful option for anyone moving between jobs or managing irregular income streams.

    Pros:

    • Flexible loan solutions for different needs
    • Offers credit card options alongside loans
    • Focuses on helping users move forward
    Cons:
    • Specific interest rates not publicly listed in all contexts

    2. Upgrade

    Upgrade – upgrade.com

    Upgrade is a major player in the personal loan market, with amounts going as high as $50,000. They cover everything from home improvements to large, one-time purchases. Their platform is built for speed. You can check your rates in just a few minutes without hurting your credit score because they use a “soft pull” for the initial check.

    This “soft pull” is a lifesaver when you’re in a tight spot. It lets you shop around for the best terms without piling on more “hard inquiries” that tank your score. They also offer a checking account that gives cash back on debit purchases, making them a decent one-stop financial hub for many people.

    If you need substantial capital to settle debts or fund a project, Upgrade offers a very streamlined experience. Since most of the process happens on a smartphone, it’s ideal for people who might not have easy access to a computer or a physical bank branch. It’s built for the digital age.

    Pros:

    • High loan amounts up to $50,000
    • Fast rate checking with no credit impact
    • Cash back rewards on checking accounts
    Cons:
    • May require higher credit for the best rates

    3. FastLendGo

    FastLendGo – fastlendgo.com

    FastLendGo works well for people needing quick cash for specific, immediate emergencies. They focus on smaller personal loans, starting as low as $500. This makes them a strong choice for things like dental bills, auto repairs, or a small utility deposit. Because the amounts are smaller, getting through the door is often easier than with a massive bank. (fastlendgo.com)

    The service is designed for simplicity. You can quickly compare options online. Whether your credit is bad, fair, or good, they have a product tier that fits your specific situation. For instance, if you have a “fair” score but can show a history of consistent income, you might find better terms here than at a major institution.

    It is a highly accessible option for someone in a pinch who needs a quick infusion of cash to stop a bad situation from getting worse. It’s about immediate relief for immediate problems.

    Pros:

    • Low entry point for small loans ($500)
    • Covers specific needs like auto or dental
    • Quick comparison of local options
    Cons:
    • Small loan focus may not suit large debts

    4. Wells Fargo

    Wells Fargo – wellsfargo.com

    Wells Fargo is a massive, established institution. They offer a full suite of services, from checking accounts to home and auto loans. They are a cornerstone of the American banking system, providing a level of stability and a physical presence that many newer fintech companies simply cannot match.

    However, if you are unemployed, getting a loan here is a steep uphill battle. Traditional banks typically demand documented proof of continuous employment for at least two years and a stable debt-to-income ratio. They aren’t usually looking to take risks on anyone without a steady, verifiable paycheck.

    That said, their wide range of products makes them a great destination for rebuilding your financial health once you find a new job. If you already have an account with them, it’s worth asking a representative about hardship programs or temporary assistance. Sometimes, a human conversation can open doors that an algorithm will keep shut.

    Pros:

    • Extensive range of financial products
    • Highly established and reputable institution
    • Comprehensive wealth management options
    Cons:
    • Tighter requirements for traditional loans

    5. NetCredit

    NetCredit – netcredit.com

    NetCredit operates on the idea that you are more than just a number in a database. They use advanced algorithms to look past a standard FICO score. This can be a lifeline for people with imperfect credit who still need significant financing. By looking at how you handle current utility bills or rent, they can see reliability that a credit report might miss.

    With loan amounts up to $10,000 and options for same-day funding, they prioritize speed. Their application process is simple, making them an attractive option for covering urgent expenses or consolidating high-interest debt. It’s a common way to take multiple small, expensive credit card balances and turn them into one single, lower-interest monthly payment.

    Pros:

    • Uses advanced algorithms for underwriting
    • Same-day funding availability
    • Loans up to $10,000 available
    Cons:
    • Subject to underwriting partner bank rules

    6. OneMain Financial

    OneMain Financial – onemainfinancial.com

    OneMain Financial is a great choice if you prefer talking to someone in person. They have about 1,300 branches across the country. They offer personal loans from $1,500 up to $30,000, with rates starting at 11.99% APR. Having a physical branch can be a huge comfort when you’re dealing with high-stress financial times.

    One of their best features is how fast you can get the money. You can see funding as soon as one hour after signing the loan. This is perfect for an emergency, like a broken furnace or an urgent medical bill, where every hour counts. Being able to sit down with a loan officer to explain your specific situation provides a level of reassurance that a website can’t provide.

    Pros:

    • Very fast funding (as soon as 1 hour)
    • Extensive branch network for in-person help
    • Predictable fixed monthly payments
    Cons:
    • Requires a loan signing process

    Understanding the Real Cost of Borrowing

    Before you sign anything, you must understand the difference between the APR (Annual Percentage Rate) and your monthly payment. The APR includes the interest rate and any mandatory fees. It is the only way to see the true cost of the loan. When you are in a crisis, you might focus only on the monthly payment, but a low payment can be a trap if the term is too long.

    A $500 monthly payment sounds manageable. But if you’re paying that for five years, you’re paying back way more than you originally borrowed. It is an illusion of affordability that can lead to a debt trap.

    Keep these three metrics in mind when you’re comparing offers:

    • Total Cost of Loan: Multiply your monthly payment by the total number of months and add any upfront fees. This is the actual price of the money.
    • Prepayment Penalties: If you get a new job and want to pay the loan off early to save on interest, check if there is a fee for doing so. Look for a “no prepayment penalty” clause.
    • Origination Fees: Some lenders take a fee out of the loan before you even see it. If you borrow $1,000 but only get $950, your interest rate is actually higher than the number they quoted you.

    Strategic Steps for Financial Recovery

    If you use a loan to bridge the gap while you’re unemployed, treat it as a tool, not a lifestyle. Use the money for the essentials: housing, food, transportation, and utilities. Don’t use it to keep up appearances or maintain a lifestyle that your current income can’t support. The goal is to buy yourself enough time to find a job without drowning in high-interest debt.

    While you navigate this period, follow these tactical steps to protect your credit and your sanity:

    1. Contact Your Current Creditors: If you can’t make a mortgage or car payment, call the lender *before* you miss the due date. Many have hardship or forbearance programs for exactly this reason.
    2. Prioritize “Survival” Expenses: If money is tight, pay your rent, utilities, and food first. Credit scores matter, but shelter and food come before credit card companies.
    3. Audit Your Subscriptions: It sounds small, but canceling a streaming service or a gym membership can save you $50 or $100 a month. That adds up when you’re on a lean budget.
    4. Document Everything: Keep a folder of every loan application, term, and email from lenders. If a dispute happens later, having a paper trail will be your best friend.

    When you’re between jobs, every dollar counts. Mistakes can be incredibly expensive. Always read the fine print and look for the total cost of borrowing, not just the monthly payment. You don’t want to be trapped by high interest when you’re already struggling.

    Resist the urge to take out several small loans from different places at once. That is a quick way to create a cycle of debt that is nearly impossible to escape. Instead, find one solution that addresses your most urgent need and has a repayment schedule that actually fits your reality.

    If things get really difficult, remember there are resources beyond high-interest loans. Sometimes negotiating with your current creditors or looking into local assistance programs can provide more relief than taking on new debt. Always weigh the long-term impact of a loan against what you need right this second.

  • Top 6 Lenders for Personal Loans for High Income Individuals in 2026

    Personal loans for high income individuals

    Top 6 Lenders for Personal Loans for High Income Individuals in 2026

    Last updated: 2026-10-16

    High earners often hit a wall when trying to access liquidity. You might see a massive salary on your tax returns, yet finding a lender that understands your complex cash flow or specific tax structures can feel like a marathon. It isn’t just about grabbing the cash. It is about finding a partner that respects your time and your financial sophistication.

    For many top-tier professionals—surgeons, corporate executives, or specialized engineers—standard algorithmic lending models often miss the mark. These models fail to capture the nuances of your actual wealth. You might have significant deferred compensation, stock options, or seasonal bonuses that don’t show up on a traditional pay stub in a way that a basic credit model understands. This discrepancy can lead to frustrating denials or suboptimal interest rates despite an impeccable net worth.

    Choosing the right lender requires looking beyond surface-level interest rates. You need to consider the speed of funding, the flexibility of repayment terms, and the ease of the digital interface. For those with significant assets, the friction of paperwork can be a dealbreaker. If you are closing a real estate deal or a private equity investment, spending three days uploading tax returns to a legacy bank is not an option.

    This list focuses on providers that balance efficiency with the specific needs of high-net-worth borrowers. We prioritized those who offer digital-first experiences and rapid deployment of capital. We want to highlight lenders that won’t slow down your momentum when you need to move quickly on an opportunity.

    1. Discover
    2. Avant
    3. JetzLoan
    4. OneMain Financial
    5. LendingPoint
    6. Upgrade

    How These Financial Providers Were Evaluated

    The evaluation process focused on the specific requirements of high-income earners. This includes the ability to secure significant loan amounts without the cumbersome requirement of collateral. Many professionals need the ability to borrow against future earnings or current assets without a hard credit pull during the initial phase. We specifically looked for lenders that utilize “soft pulls” for the pre-qualification stage. This allows you to run the numbers without any risk to your credit score.

    Speed of capital deployment was another critical metric. A high-earner might need funds for a sudden real estate opportunity or a strategic investment. Therefore, lenders that offer rapid funding, sometimes within twenty-four hours or even a single hour, were prioritized. We also looked at the transparency of their digital application processes to ensure no hidden surprises. A lender that hides “origination fees” deep within a 20-page PDF is a red flag for a borrower who values efficiency and clarity.

    Furthermore, we examined the scalability of the loan products. A lender that only offers $5,000 might be useful for a minor repair, but it fails to serve the needs of someone looking to consolidate high-interest debt or fund a significant lifestyle upgrade. We sought out providers that offer a meaningful ceiling on loan amounts, typically $30,000 or higher. This ensures the liquidity provided is actually useful for high-net-worth strategic planning.

    Comparative Overview of Top Lenders

    Lender Name Max Loan Amount Funding Speed Interest Rate / APR Info Credit Check Impact
    Discover $40,000 Next business day 6.99% – 24.99% No impact for pre-approval
    Avant See site See site See site See site
    JetzLoan $50,000 As little as 24 hours See site No hard credit pull
    OneMain Financial $30,000 As soon as 1 hour Starting at 11.99% APR No impact for checking
    LendingPoint $36,500 See site See site No impact for checking
    Upgrade $50,000 Fast funding See site No impact for checking

    Ranking the Best Lenders for High Earners

    1. Discover

    Discover – discover.com

    Discover is a solid choice for those who value a brand backed by the full faith and credit of the U.S. Government. Their personal loans are straightforward, offering amounts from $2,500 up to $40,000. It is a reliable choice for those who want stability and a well-established institution behind their debt. If you are tired of fintech startups that might pivot their business model overnight, Discover offers a sense of permanence and institutional security.

    The platform is incredibly user-friendly, allowing for a quick check to see if you are pre-approved. This is vital for high-income individuals who do not want to see their credit score take a hit just to see what kind of terms they might qualify for. It is a low-friction way to explore your options. The digital interface is streamlined, minimizing the time spent navigating through unnecessary menus. This is a luxury in itself for the time-constrained professional.

    Pros:

    • Funds can be sent as early as the next business day.
    • No fees and flexible terms are available.
    • Pre-approval check does not impact your credit score.

    Cons:

    • Maximum loan amount is capped at $40,000.

    2. Avant

    Avant – avant.com

    Avant focuses on providing tailored solutions for people who are actively moving their financial lives forward. They offer a variety of products, including credit cards and loans designed for debt consolidation or home improvements. It is a versatile option for those who need a lender that can adapt to different life stages. For example, your debt-to-income ratio might fluctuate during a transition from a high-earning associate to a partner in a firm.

    The company emphasizes flexible choices and friendly support, making it easier to navigate the complexities of personal debt. Whether you are looking for a quick fix for an unexpected expense or a long-term strategy for debt management, their tools are built to simplify the journey. Their approach is less about “one size fits all” and more about providing a menu of options that align with your specific financial velocity.

    Pros:

    • Flexible loan solutions for various needs.
    • User-friendly digital tools for managing finances.
    • Provides multiple paths for debt management.

    Cons:

    • Specific loan terms and limits are not explicitly detailed.

    3. JetzLoan

    JetzLoan – jetzloan.com

    For the professional who needs capital yesterday, JetzLoan is a high-speed contender. They connect you with top lenders in minutes and can facilitate funding in as little as twenty-four hours. This is perfect for those who find the traditional banking pace to be far too sluggish for their lifestyle. If you have been presented with a time-sensitive investment opportunity—perhaps a real estate auction or a private placement—the speed offered here is a significant competitive advantage.

    The process is incredibly streamlined, taking less than two minutes to complete a simple form. With a maximum loan amount of $50,000, they cater to significant needs without the headache of a hard credit pull during the initial rate check. This “marketplace” model allows you to see a broad spectrum of options without the repetitive task of applying to multiple banks individually. It saves you hours of administrative overhead.

    Pros:

    • Extremely fast funding, potentially within 24 hours.
    • No hard credit pull required for initial rate check.
    • High maximum loan amount of $50,000.

    Cons:

    • The platform acts as a connector rather than a direct lender.

    4. OneMain Financial

    OneMain Financial – onemainfinancial.com

    OneMain Financial is a powerhouse for those who prefer a mix of digital ease and human interaction. They offer personal loans ranging from $1,500 to $30,000, with rates starting at 11.99% APR. Their ability to provide money as soon as one hour after signing is a massive selling point for urgent needs. This level of speed is rare in the unsecured loan market and makes them a top choice for emergency liquidity.

    If you prefer talking to a real person, you can visit one of their 1,300 branches. This hybrid model is ideal for high earners who might want the convenience of an app but still value the security of a face-to-face meeting when dealing with significant financial matters. Having a physical location to visit can provide peace of mind, especially if you need to discuss complex repayment structures or specific documentation that a purely digital lender might reject.

    Pros:

    • Rapid funding, potentially in just one hour.
    • Extensive branch network for in-person support.
    • Flexible terms from 24 to 60 months.

    Cons:

    • Rates for unsecured loans can be higher than secured options.

    5. LendingPoint

    LendingPoint – lendingpoint.com

    LendingPoint positions itself as a solution for various life events, from weddings to medical expenses. They offer loans between $1,000 and $36,500, providing a solid middle ground for those who need more than a small micro-loan but less than a massive mortgage. Their underwriting process is designed to be more sophisticated than basic consumer lenders, often looking at a broader picture of your financial health.

    The platform is designed to make money easy, with a process that allows you to check your rate without impacting your credit score. This allows you to shop around and compare your options against other lenders without any financial penalty to your credit profile. This ability to “window shop” is critical for high-earners who are often managing multiple lines of credit and need to be precise about which debt they are taking on and at what cost.

    Pros:

    • Wide range of loan purposes supported.
    • Check rates without impacting credit scores.
    • Significant loan amounts up to $36,500.

    Cons:

    • Loan amounts are lower than some specialized lenders.

    6. Upgrade

    Upgrade – upgrade.com

    Upgrade is a comprehensive financial tool for the modern consumer, offering personal loans up to $50,000. They focus on speed and high-tech integration, allowing you to see rates in minutes. It is an excellent choice for those who want to manage their loans, savings, and checking in one ecosystem. Their technology-forward approach reduces the “friction of friction,” meaning fewer steps between application and disbursement.

    Their ecosystem is quite robust, with options to earn cash back on various transactions and high APY on savings. It is a “one-stop-shop” approach that appeals to high earners who want to consolidate their financial life into a single, efficient digital interface. By centralizing these functions, you can get a clearer view of your total liquidity at any given moment, which is essential for sophisticated cash flow management.

    Pros:

    • Large loan limit of up to $50,000.
    • Integrated financial ecosystem with savings and checking.
    • Fast rate checking with no credit impact.

    Cons:

    • The complexity of the ecosystem might feel overwhelming to some.

    Strategic Use of Personal Loans for High Earners

    For those with high income, personal loans should not just be viewed as “debt,” but as a strategic tool for capital management. When used correctly, these loans can serve as a bridge to larger wealth-building opportunities. Consider the following strategic applications:

    • Arbitrage Opportunities: If you encounter a time-sensitive investment—such as a distressed real estate sale or a private equity opportunity—a personal loan can provide the necessary liquidity to secure the deal while you wait for your quarterly bonus or the sale of another asset to close. The cost of the interest is weighed against the potential upside of the investment.

    • Tax Optimization: While personal loans are not tax-deductible in the same way mortgage interest is, they can be used to manage cash flow during high-tax years. For example, using a loan to fund a major capital expense now might allow you to defer using your own cash reserves, keeping your liquidity available for other high-yield investments.

    • Debt Refinancing: High earners often carry multiple lines of credit, including premium credit cards with varying interest rates. Consolidating these into a single, lower-interest personal loan can simplify your monthly cash flow and reduce the total interest paid over time.

    Avoiding Pitfalls in Personal Lending

    Even with a high income, it is easy to make mistakes that can erode your wealth over time. One of the most common errors is ignoring the total cost of credit in favor of a low monthly payment. When you are looking at a $50,000 loan, a difference of 2% in interest can result in thousands of dollars of wasted capital over the life of the loan. Always look at the APR, not just the monthly installment, to see the true cost of your borrowing. The APR accounts for both the interest rate and any mandatory fees, giving you the most accurate picture of the cost.

    Another mistake is failing to compare the funding speed with the necessity of the funds. If you need money for an immediate opportunity, a slightly higher rate might be worth it if the capital arrives in an hour. For example, if a business opportunity requires a 24-hour turnaround, a 12% loan delivered in an hour is far more valuable than a 7% loan that takes ten days to process. Conversely, for long-term debt consolidation, prioritize the lowest possible APR over speed.

    Lastly, keep an eye on the fine print regarding prepayment penalties. High earners often find themselves with extra liquidity and may want to pay off a loan early to save on interest. If your lender charges a fee for doing this, you might find that the “cheap” loan becomes quite expensive in the end. Before signing, ask explicitly: “Is there a penalty for paying this loan off in full within the first twelve months?” For a high-income individual with fluctuating cash inflows, this flexibility is a non-negotiable requirement for a smart lending partner.

  • Top 6 Lenders for Personal Loans for Credit Score Under 600 in 2026

    Personal loans for credit score under 600

    Top 6 Lenders for Personal Loans for Credit Score Under 600 in 2026

    Last updated: 2026-10-16

    Trying to manage your money when your credit score dips below 600 feels like walking through a thick fog. Most traditional banks tend to slam the door shut. This leaves anyone in need of quick capital searching for a lifeline. It is a stressful position to be in, especially when unexpected expenses arise, such as an urgent car repair, a medical bill, or a sudden gap in employment.

    When you are in this position, the standard loan products offered by major institutions like Chase or Wells Fargo often feel out of reach. Their automated underwriting systems are programmed to prioritize high FICO scores and extensive credit histories. They aren’t really built to look at the person behind the number.

    Finding the right lender requires more than just looking at interest rates. You must weigh speed, loan amounts, and how much a lender cares about your past mistakes versus your current income. For instance, a lender might be willing to overlook a previous bankruptcy or a late payment if they see a consistent, verifiable stream of income from a current employer.

    This ranking aims to highlight the most viable options available for those working to rebuild their financial reputation. We have looked at several providers to see who actually helps when things get tough. Here are the top contenders for 2026.

    1. FastLendGo
    2. Avant
    3. Prosper
    4. Max Cash
    5. Upgrade
    6. LendingPoint

    The Selection Process for Sub-600 Credit Lenders

    The criteria used to evaluate these lenders focus heavily on accessibility for borrowers with fair or poor credit. We looked at the minimum loan amounts offered and the speed of funding. Immediate cash is often the primary driver for those seeking sub-600 loans. If you are facing an eviction notice or a utility shut-off, you don’t have time to wait ten business days for a decision.

    You need a lender that operates with high-speed digital underwriting. We also examined the specific niches each lender serves. Some specialize in small, emergency cash advances, while others focus on larger debt consolidation efforts. Understanding whether a lender wants to see a high income or simply a steady history of employment helps determine which application is most likely to yield an approval.

    For example, a lender might require a minimum monthly income of $2,500. Another might be satisfied with any steady income that can be verified through bank statements rather than traditional pay stubs. This distinction is vital when you are trying to secure funds on a tight deadline.

    Lender Name Loan Amounts Credit Requirements Funding Speed
    FastLendGo $500 – $5,000+ Bad/Fair Credit Fast Access
    Avant See site Around 580 See site
    Prosper $2,000 – $50,000 See site See site
    Max Cash $250 – $10,000+ Bad Credit In Minutes
    Upgrade Up to $50,000 See site See site
    LendingPoint $1,000 – $36,500 See site See site

    1. FastLendGo

    FastLendGo – fastlendgo.com

    FastLendGo positions itself as a versatile partner for those needing quick cash to navigate life’s sudden hurdles. They offer a wide range of options, from small $500 loans to larger sums of $5,000 or more. This flexibility is a godsend for someone who just needs to cover a quick auto repair or a dental bill. Because they cater to specific needs, the application process is often streamlined to focus on the necessity of the funds rather than a deep dive into a decade of credit history. (fastlendgo.com)

    This lender is particularly useful for individuals with bad or fair credit who might be ignored elsewhere. They cater to various needs, including motorcycle loans and roof financing. If you are looking for a way to compare local options quickly, this platform simplifies the often overwhelming search process. By specializing in niche lending, they can offer products that traditional personal loan providers won’t touch, such as collateralized options that use your vehicle or property to secure the funds.

    Pros:

    • Wide variety of loan purposes including emergency and auto repairs.
    • Options for small-dollar amounts starting at $500.
    • Targets individuals with bad or fair credit.

    Cons:

    • Limited information provided regarding specific interest rate ranges.

    2. Avant

    Avant – avant.com

    Avant operates with a philosophy of helping people move forward financially, even when the road gets bumpy. They offer both personal loans and credit cards designed to help with debt consolidation or unexpected expenses. Their tools are built to simplify the journey toward better financial health, providing a digital interface that guides you through the necessary documentation without the need for a physical branch visit.

    They are a solid choice for those hovering around the 580 credit score mark. Instead of judging you solely on a number, they focus on providing solutions like installment loans to help manage your monthly budget. Their model is designed to look at the “whole person,” meaning they may consider your debt-to-income ratio more heavily than a single late payment from two years ago. This is a proactive approach to credit management that prioritizes your ability to repay over your history of struggle.

    Pros:

    • Offers both loans and credit card solutions.
    • Focuses on debt consolidation and home improvement.
    • User-friendly digital tools for financial management.

    Cons:

    • Credit requirements may still exclude those with very low scores.

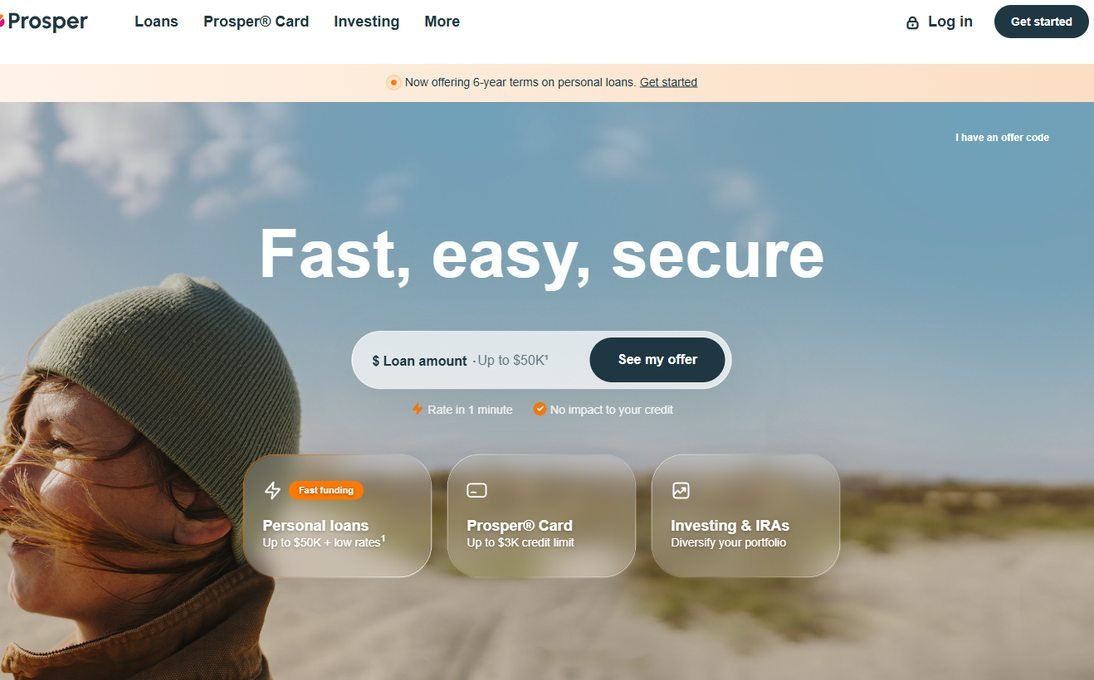
    3. Prosper

    Prosper – prosper.com

    Prosper is a well-known name in the peer-to-peer (P2P) lending space, offering a different flavor of financing. Instead of a traditional bank, you are often borrowing from other individuals who are looking to earn interest on their extra cash. This can sometimes lead to more flexibility for those with non-traditional financial profiles, as the “lenders” in this scenario are often more willing to take on risk in exchange for higher potential returns.

    The platform offers significant loan amounts, ranging from $2,000 all the way up to $50,000. This makes them a strong contender for major life events like weddings, significant debt restructuring, or large home improvements. Because the funding comes from multiple individual investors rather than a single institutional pool, the approval criteria can sometimes feel more nuanced. Their reputation is backed by high ratings from long-term customers who appreciate the transparent marketplace model.

    Pros:

    • High maximum loan amounts up to $50,000.
    • Peer-to-peer model can offer diverse options.
    • Strong customer rating on third-party review sites.

    Cons:

    • The peer-to-peer model can result in variable approval timelines.

    4. Max Cash

    Max Cash – maxcash.com

    When you are staring at a sudden bill and the clock is ticking, Max Cash steps into the ring. They specialize in speed, offering installment loans and even title loans in a matter of minutes. This is clearly designed for the “emergency” scenario where every second counts—think a sudden transmission failure in your car that prevents you from getting to work, or an urgent medical procedure that requires a deposit.

    Their loan amounts are highly segmented, starting as low as $250. This makes them an excellent option for those who don’t want to take on more debt than absolutely necessary. If you only need $300 to cover a utility bill, taking out a $5,000 loan is a recipe for disaster. Max Cash allows for surgical precision in borrowing. They provide a “relief” focused service for those in urgent financial straits who need liquidity immediately without the bureaucracy of a major bank.

    Pros:

    • Extremely fast processing for emergency needs.
    • Very low entry point for small loans ($250).
    • Wide range of products including title loans.

    Cons:

    • High-speed, small-dollar loans often carry very high interest rates.

    5. Upgrade

    Upgrade – upgrade.com

    Upgrade is more than just a lender; they are a full-scale financial services provider. They offer personal loans, credit cards, and even checking accounts. This makes them a great “one-stop shop” for someone looking to consolidate their financial life into one ecosystem. By bringing multiple financial products under one roof, you can often find more streamlined management of your overall cash flow.

    With a maximum loan amount of $50,000, they are suitable for significant life changes like business ventures or large purchases. Their model is built around helping customers earn rewards and manage their cash flow more effectively through their various products. They often use a combination of credit scores and income verification to determine eligibility, which can be a benefit for those who have a high income but a lower credit score due to past mishaps.

    Pros:

    • Comprehensive suite of products including checking accounts.
    • High loan limits up to $50,000.
    • Offers cash back incentives on certain products.

    Cons:

    • May require a more stable financial profile than specialized sub-600 lenders.

    6. LendingPoint

    LendingPoint focuses on helping users unlock possibilities through personalized personal loans. They offer amounts ranging from $1,000 to $36,500, making them a middle-ground option for those who need more than a quick cash advance but less than a major bank loan. They target consumers who are looking for a way to bridge the gap between being “unbankable” and having a standard prime credit score.

    Their application process is designed to be efficient, allowing you to check your rate without impacting your credit score. This is a massive advantage for someone with a sub-600 score who cannot afford to lose any more points to hard inquiries. Every time you apply for credit and are denied, it leaves a mark on your report. LendingPoint’s “soft pull” feature allows you to shop for terms with confidence and zero risk to your credit standing.

    Pros:

    • Check rates without affecting your credit score.
    • Significant loan amounts up to $36,500.
    • Clear purposes for loans like medical or travel expenses.

    Cons:

    • Credit requirements are not explicitly stated as “low credit” friendly.

    Understanding the True Cost of Sub-600 Borrowing

    When your credit is below 600, you aren’t just paying for the money you borrow; you are paying for the risk the lender is taking. It is essential to understand the concept of Annual Percentage Rate (APR). While a standard bank loan might have an APR of 8% to 12%, a sub-600 lender might offer rates ranging from 25% to 36% or even higher for short-term products. This difference can mean the difference between a manageable monthly payment and a debt cycle that is impossible to escape.

    Consider this comparison: borrowing $5,000 at 10% interest over 3 years results in much less total interest paid than borrowing $5,000 at 30% interest over 3 years. In the latter scenario, you could end up paying back nearly $8,000 for a $5,000 loan. Before signing any agreement, ask for a “Truth in Lending” disclosure. This document is legally required to show you exactly how much interest you will pay in total dollars over the life of the loan. If the total interest amount makes your eyes widen, look for a smaller loan amount or a different lender.

    Strategies to Improve Your Chances of Approval

    While you cannot instantly change a low credit score, you can change how you present yourself to a lender. Lenders look for stability. If you are applying for a loan with a 550 score, providing proof of consistent employment through the last six months of pay stubs can be more influential than the score itself. Stability suggests a lower risk of default, which is the primary concern for any lender.
    Another powerful strategy is the “pre-qualification” phase. Never, under any circumstances, submit a full application until you have used a pre-qualification tool. As mentioned earlier, a “hard inquiry” happens when you officially apply for credit and can drop your score by several points. A “soft inquiry” happens when you check your rate or use a comparison tool. You should perform several soft inquiries to find the best rate, and only once you have found a lender that meets your needs should you proceed to the formal application. This methodical approach protects your credit score while you hunt for the most affordable capital.

    Additionally, always read the fine print regarding repayment terms. Some lenders might offer a low monthly payment, but if that term is stretched over several years, you will end up paying back double or triple what you originally borrowed. Aim for the shortest term you can realistically afford to minimize the total interest paid. If you can afford to pay an extra $50 toward your principal each month, you can drastically reduce the total cost of the loan and the time you spend in debt.

  • Best Lenders for a 620 Credit Score Personal Loan in 2026

    620 credit score personal loan

    Best Lenders for a 620 Credit Score Personal Loan in 2026

    Last updated: 2026-10-16

    Trying to manage money with a 620 credit score often feels like driving through a heavy fog. You know you can pay your bills on time, but big banks tend to look the other way when they see a “fair” rating on your report. It is a frustrating spot to be stuck in. You are caught between high-interest traps and the strict rules of premium lenders.

    When looking for a lifeline, you shouldn’t just settle for anyone who says yes. The real goal is finding a lender that offers a way forward without burying you under predatory interest rates. This list looks at the top contenders for 2026 for anyone sitting at that 620 threshold, focusing on how fast they move and how transparent they are.

    1. JetzLoan
    2. Max Cash
    3. Avant
    4. Upgrade
    5. LendingPoint
    6. United Finance
    7. Prosper

    Evaluating Fair Credit Loan Options

    To figure out which lenders actually cater to people with fair credit, we looked at a few specific things. We tracked how quickly a borrower can go from an initial inquiry to having actual cash in their hand. Life’s emergencies don’t wait for a week-long underwriting process, so speed matters.

    Checking rates without a hard inquiry is another big deal. A 620 score is a delicate thing, and every unnecessary hard pull can nudge that number down a few points. We prioritized lenders that offer a “soft” look at your credit, so you can shop around without hurting your score immediately.

    The math is simple. If a lender takes too long or requires a hard pull just to give you a quote, they might not be the right fit for someone trying to protect a borderline score. You want options that let you compare costs without any immediate penalty.

    Lender Name Loan Amount Range Funding Speed Credit Impact Check
    JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
    Max Cash $250 – $10,000+ Minutes Free inquiry
    Avant See site See site See site
    Upgrade Up to $50,000 Fast funding Won’t impact score
    LendingPoint $1,000 – $36,500 See site Does not impact credit score
    United Finance Up to $20,000 Quick approval See site
    Prosper $2,000 – $50,000 See site No impact to credit

    Ranking of Top Lenders

    1. JetzLoan

    JetzLoan – jetzloan.com

    JetzLoan is a go-to for people who need cash yesterday. They connect borrowers with various top personal loan lenders, which cuts out the exhausting search for a match. It is a digital-first setup built for a fast-paced world where waiting days for a response isn’t an option. (jetzloan.com)

    This service works well if you need to consolidate debt or cover a sudden car repair. You can receive funds within a 24-hour window, making it a strong choice for urgent needs. The application is lean, taking only about two minutes to get things moving.

    It is not a direct lender, so keep that in mind. They act as a middleman to find you the best fit from their network rather than being the sole source of the money.

    Pros:
    • Funds can be deposited in as little as 24 hours.
    • No hard credit pull during the initial rate check.
    • High maximum loan limit of $35,000.
    Cons:
    • Connects to other lenders rather than being the sole source.

    2. Max Cash

    Max Cash – maxcash.com

    Max Cash is a versatile shop for many different financial products. Whether you need a small installment loan or a larger cash advance, their platform is built to find relief quickly. They handle everything from tiny emergency loans to car financing.

    The platform is very accessible. You can find anything from a $250 amount to significant sums over $10,000. Since they offer free, no-obligation inquiries, you can look around without worrying about a sudden dip in your credit score. It is a great tool when you are in a pinch.

    Just be aware that the variety of products can feel a bit overwhelming. There are a lot of moving parts to keep track of when you are browsing their options.

    Pros:
    • Extremely low entry point starting at $250.
    • Very fast processing time, often within minutes.
    • Wide range of products including title loans and cash advances.
    Cons:
    • The variety of products can be overwhelming and complex.

    3. Avant

    Avant – avant.com

    Avant focuses on helping people move their financial lives forward. They specialize in things like debt consolidation and emergency loans for those who might not fit the mold of a traditional bank. Their goal is to help you reach specific milestones through structured installment loans.

    This lender is a solid pick if your score is in the 580 to 700 range. They offer a sense of stability, aiming to provide clarity instead of just a quick transaction. It is a more holistic approach for the middle-ground borrower.

    They aren’t quite as loose as some niche “bad credit” lenders. You might find that their requirements are a bit more specific than others in the market.

    Pros:
    • Specific loan products for debt consolidation and home improvement.
    • Designed for borrowers in the 580-700 credit score range.
    • Focuses on long-term financial movement.
    Cons:
    • May have stricter requirements than niche “bad credit” lenders.

    4. Upgrade

    Upgrade – upgrade.com

    Upgrade is a heavy hitter in the online world. They offer a whole suite of services, including personal loans, credit cards, and savings accounts. They are well-known for being fast and offering fixed rates, which helps when you are trying to budget for the future.

    If you need to borrow up to $50,000, Upgrade offers a very direct path to funding. Their system shows you your rate in minutes without hurting your credit score. They even have perks like cash back on certain debit purchases for their checking customers.

    Because they have so many different products, the sheer number of options can sometimes get confusing. You might want to take a moment to figure out exactly which tool fits your situation best.

    Pros:
    • High loan ceilings reaching up to $50,000.
    • Fixed rates provide predictable monthly payments.
    • Fast funding and quick rate checks.
    Cons:
    • Complexity of multiple products might be confusing.

    5. LendingPoint

    LendingPoint – lendingpoint.com

    LendingPoint makes the money side of things simple with a straightforward application. They target people who need to cover urgent expenses, like medical bills, a wedding, or travel costs. Their range is substantial, offering loans from $1,000 up to $36,500.

    They emphasize being transparent. You can check your rates without impacting your credit score, which is vital if you have a 620 score and need to be careful with your credit health. It makes navigating a large purchase much less stressful.

    Just be prepared for the paperwork. The application process might require you to provide more detailed documentation than some of the faster, lighter lenders.

    Pros:
    • Loan amounts are tailored for significant life events.
    • Soft credit checks allow for safe rate comparison.
    • Clear distinction for various loan purposes.
    Cons:
    • The application process may require more detailed documentation.

    6. United Finance

    United Finance – unitedfinance.com

    United Finance has been around since 1922. That kind of longevity provides a level of stability that many new fintech companies simply cannot match. They offer a more traditional, personalized experience, focusing on personal and auto loans that fit a specific budget.

    For those looking to build or rebuild credit, they offer a strategic way to manage debt through installment loans. You get a sense of peace of mind working with dedicated, friendly lenders. It is a great option if you prefer a more human touch in your banking.

    They might not have the instant, high-tech speed of the newer apps, but they have the experience to back it up. It is a trade-off between cutting-edge speed and old-school reliability.

    Pros:
    • Decades of experience and stability in the market.
    • Offers both personal and auto loan options.
    • Focuses on building a sustainable budget.
    Cons:
    • May lack the instant, high-tech speed of newer competitors.

    7. Prosper

    Prosper – prosper.com

    Prosper is a big name in the peer-to-peer lending space. They are known for competitive rates and a strong market presence. They offer personal loans from $2,000 to $50,000, often with flexible repayment terms.

    They are a strong choice if you want to see your rates quickly without any credit impact. The platform is built for efficiency, making it easy to find the funds you need when you need them most. It is a very modern, tech-savvy way to handle debt.

    Since it is a peer-to-peer model, the approval process can sometimes feel different than a traditional bank. There are different nuances to how they evaluate your application.

    Pros:
    • High loan limits up to $50,000.
    • Offers a variety of terms, including 6-year options.
    • Quick and easy digital interface.
    Cons:
    • Peer-to-peer models can sometimes have different approval nuances.

    Navigating Your Loan Search

    Picking the right lender is a balancing act. You have to weigh your immediate needs against your long-term financial health. If there is an emergency, speed is your main driver. If you are consolidating debt, you need to look very closely at the total cost and the interest rate.

    Don’t fall into the trap of only looking at the monthly payment. A lower monthly payment usually means a much longer loan term. This can result in you paying thousands of dollars more in interest over the life of the loan. Always ask for the total repayment amount before you sign anything.

    Another mistake is applying for multiple loans at once. While checking your rate is usually safe, submitting a full application triggers a “hard” pull. Do your research, compare the rates using the “soft pull” options first, and only commit when you find the best fit.

  • Top 6 Lenders for a 500 Credit Score Personal Loan in 2026

    500 credit score personal loan

    Top 6 Lenders for a 500 Credit Score Personal Loan in 2026

    Last updated: 2026-10-16

    Walking through a financial slump with a 500 credit score feels like trying to find your way through a thick fog without a compass. Many people assume a low score is a locked door, but the current market suggests it is often just a hurdle. Finding a lender that looks past a single number is the key to finding relief.

    A 500 score typically falls into the “very poor” category. This means traditional mortgage lenders or high-tier credit card issuers will likely issue immediate denials. However, you are not entirely shut out of the credit market. You simply must shift your strategy from “standard” lenders to “specialty” lenders.

    When searching for a loan, the goal isn’t just to get the cash. You need to secure terms that won’t sink your future. High interest rates can turn a small debt into a mountain of trouble. For example, a $5,000 loan at a 25% APR is vastly different from a $5,000 loan at 36% APR when viewed over a 36-month repayment period. The latter can result in thousands of dollars in additional interest that could have gone toward your savings or debt reduction. This selection focuses on lenders that prioritize accessibility and speed for those working to rebuild their financial standing.

    1. Avant
    2. OneMain Financial
    3. FastLendGo
    4. Reprise
    5. United Finance
    6. OppLoans

    How These Lenders Were Evaluated

    The comparison process focused on accessibility for borrowers in the “poor” credit range. Since a 500 score often limits access to traditional bank loans, the evaluation looked heavily at lenders known for catering to weak credit profiles. We prioritized companies that offer clear paths to application without immediately penalizing your FICO score during the initial inquiry.

    A “soft pull” allows you to see your potential rate and terms without a “hard pull” hitting your report. This is vital when your score is already under pressure. You can check your options without making the situation worse.

    Speed of funding and transparency in terms were the next critical pillars. A borrower in an emergency situation—facing an unexpected car repair, a medical bill, or an urgent utility payment—needs money yesterday. Therefore, lenders that offer quick decision-making or same-day funding were given higher visibility in this ranking, provided they maintained reasonable structures for repayment. We specifically looked at the “time-to-cash” metric, which measures the duration from the moment you hit “submit” on an application to the moment the funds are available in your checking account.

    Understanding the True Cost of Low-Credit Loans

    Before committing to a lender from this list, it is essential to understand the mathematical reality of high-interest borrowing. When you have a 500 credit score, lenders view you as a high-risk borrower. To compensate for that risk, they charge higher Annual Percentage Rates (APRs). It is vital to distinguish between the interest rate and the APR. The APR includes the interest rate plus any lender fees or origination costs, providing a more accurate picture of what you will actually pay.

    Consider the following comparison of loan scenarios for a borrower with a 500 score:

    Loan Amount Interest Rate (APR) Term Length Monthly Payment Total Interest Paid
    $3,000 15% (Good Credit) 24 Months $145.46 $491.04
    $3,000 30% (Fair Credit) 24 Months $171.18 $1,108.32
    $3,000 45% (Poor Credit) 24 Months $199.63 $1,791.12

    As shown above, doubling the interest rate can more than triple the total cost of the loan. This is why selecting a lender that helps you rebuild your credit—rather than one that simply extracts maximum interest—is the most important decision you will make in this process.

    Comparison of Leading Lenders

    Lender Name Loan Amounts Terms Funding Speed Credit Requirement
    Avant See site See site See site Weak Credit Friendly
    OneMain Financial $1,500 – $30,000 24 – 60 months As soon as 1 hour See site
    FastLendGo See site See site See site Bad Credit/No Credit
    Reprise See site See site See site See site
    United Finance Up to $20,000 See site See site See site
    OppLoans See site See site Same-day funding Does not affect FICO

    Ranking of Top Lenders

    1. Avant

    Avant – avant.com

    Avant positions itself as a partner for those looking to move forward financially. They offer specialized solutions, including credit cards and installment loans, designed to fit various life stages. Their focus is on providing tools that help users manage debt or handle unexpected expenses.

    Unlike many predatory lenders that only offer short-term “payday” style loans, Avant aims to build a long-term relationship with the borrower. This lender is a strong choice for individuals who need more than just a simple loan. Their ecosystem of products, including debt consolidation options, makes them a versatile player for those looking to reorganize their financial life.

    If you are currently juggling multiple high-interest credit card balances, an Avant installment loan could potentially consolidate those payments into a single, more manageable monthly bill, provided the interest rate is favorable.

    Pros:
    • Offers diverse financial tools like credit cards and debt consolidation.
    • Designed to help users move toward financial goals.
    • Flexible solutions for different life stages.
    Cons:
    • Specific interest rates and terms are not explicitly listed for all credit tiers.

    2. OneMain Financial

    OneMain Financial – onemainfinancial.com

    OneMain Financial is a powerhouse for those who need a human touch. With over 1,300 branches, they offer a physical presence that many online lenders lack. This is a significant advantage for borrowers who may have complex financial situations—such as being self-employed or having unconventional income sources—that a computer algorithm might struggle to verify.

    In a branch setting, you can sit down with a loan officer to explain your situation. This can sometimes lead to better terms than a purely automated process. They provide personal loans ranging from $1,500 to $30,000, making them a robust option for larger needs such as home repairs or debt consolidation.

    If you need funds quickly, they can provide money as soon as one hour after the loan is signed. You just have to complete the necessary paperwork and verification in person.

    Pros:
    • Large network of physical branches for in-person support.
    • Fast funding, potentially within one hour of signing.
    • High loan amounts up to $30,000.
    Cons:
    • Requires a response to a mailed offer or specific branch visit for some options.

    3. FastLendGo

    FastLendGo – fastlendgo.com

    FastLendGo acts as a digital bridge, helping borrowers quickly compare local personal loan options. Instead of you spending hours calling different banks, FastLendGo aggregates various offers into a single streamlined platform. They cater to a wide variety of needs, from small $500 loans for emergency repairs to larger amounts for auto or roof repairs.

    Their platform is built for speed and ease of use. It is optimized for mobile users who need to apply on the go. They specifically target those in tough spots, offering solutions for bad credit and even those with no credit history. This makes them a go-to for those who need to find a lender “near me” without the traditional wait times associated with brick-and-mortar institutions.

    By using a comparison model, you are empowered to see which lender offers the most competitive rate for your specific credit profile. You get to see the whole picture at once.

    Pros:
    • Covers a wide range of loan purposes like auto and dental.
    • Options available for various credit levels, including no credit.
    • Quick comparison of local options.
    Cons:
    • The platform serves as a comparison tool, meaning terms depend on the specific lender matched.

    4. Reprise

    Reprise – reprise.com

    Reprise stands out by leveraging high-tech AI tools to manage demos and data. While their primary focus is on an enterprise demo creation platform, they represent the intersection of advanced technology and professional service. In an era where financial services are increasingly being automated, Reprise serves as a reminder of how sophisticated data management has become across all sectors.

    For the tech-savvy professional, they offer capabilities like data injection and full clones. They are less a traditional personal lender and more a specialized tool for high-level business presentation and management. This makes them a unique entry in a list that otherwise focuses on consumer financing, highlighting the diverse landscape of modern fintech.

    Pros:
    • Advanced AI toolset for demo creation.
    • High-level data injection capabilities.
    • Efficient for professional presentation management.
    Cons:
    • Not a traditional consumer personal loan provider for individual debt.

    5. United Finance

    United Finance – unitedfinance.com

    United Finance is a seasoned veteran, having been around since 1922. They specialize in personal and auto loans that are designed to be simple and accessible. Their reputation is built on decades of providing stability to their clients. This is a refreshing change in a market often dominated by “flashy” but unstable fintech startups.

    Their longevity suggests a deep understanding of the lending cycle and risk management. They offer personal loans up to $20,000. They also provide high-yield certificates for residents of Oregon. This dual focus on lending and savings/investment products makes them a solid choice for someone looking for a traditional, long-standing financial institution.

    Pros:
    • Extremely long-standing history and stability.
    • Offers both personal and auto loans.
    • Provides investment options like high-yield certificates.
    Cons:
    • Geographic limitations may apply to certain products like investment certificates.

    6. OppLoans

    OppLoans – opploans.com

    OppLoans is built for speed and minimal impact on your credit score. One of their biggest selling points is that applying does not affect your FICO score. This is a godsend for someone trying to protect their 500 score. When you are in the process of rebuilding, every single point counts.

    A “hard inquiry” can drop a score by several points, so being able to check your eligibility without that penalty is a massive advantage. They work with bank partners to offer quick decisions. If you are in a pinch, they offer same-day funding. Their application process is streamlined, often providing decisions within minutes.

    This is ideal for urgent financial situations where a delay of even 24 hours could result in a late fee or a service disconnection. It is built for when you need a solution right now.

    Pros:
    • Applying does not affect FICO credit score.
    • Same-day funding available for approved applicants.
    • Quick decision-making process.
    Cons:
    • Typically aimed at high-need, short-term situations rather than long-term wealth building.

    Navigating Your Loan Search

    When you are staring at a 500 credit score, the temptation to grab the first offer is massive. However, the “easiest” loan isn’t always the best one. It is vital to read the fine print regarding the total cost of borrowing. A small loan that feels easy to get can become a heavy burden if the interest rates are predatory.

    Always check for “origination fees”—these are upfront costs taken out of your loan amount. For example, if you borrow $1,000 but the lender takes a $100 origination fee, you only receive $900. However, you still owe interest on the full $1,000. That is a hidden cost that can sting later.

    One common mistake is ignoring the difference between a hard and soft credit pull. Always look for lenders that allow you to check your eligibility without a hard inquiry. This allows you to shop around and compare rates without further damaging your score. Use this period to gather multiple quotes. Even if they are from different lenders, comparing the APRs is the only way to ensure you aren’t overpaying for the privilege of borrowing.

    Another pitfall is failing to consider the repayment timeline. A shorter term means higher monthly payments, while a longer term means more interest paid over the life of the loan. If you choose a 60-month term just to make the monthly payment affordable, you might end up paying back nearly double the amount you originally borrowed. Always pick a term that fits your monthly budget comfortably. Leave enough room to build savings and improve that score for the future. The ultimate goal is to use this loan to bridge a gap, not to create a permanent cycle of debt.

  • Top 6 Lenders for a 520 Credit Score Personal Loan in 2026

    520 credit score personal loan

    Top 6 Lenders for a 520 Credit Score Personal Loan in 2026

    Last updated: 2026-10-16

    Hitting a 520 credit score feels like trying to run a marathon through waist-deep mud. The financial world often slams doors in your face when your number dips into the low 500s. It is an exhausting cycle of searching for help only to find more rejection letters in the mail.

    At this level, you are likely dealing with a history of missed payments, high credit utilization, or perhaps a recent bankruptcy or collections account. The psychological toll of being told “no” by every major institution can be just as heavy as the financial burden itself.
    This ranking focuses on lenders that actually look beyond that single, stubborn number. When you are staring at a low score, you need speed, clarity, and a realistic chance at approval. You don’t have time for a three-week manual review process when an emergency repair or a medical bill is due tomorrow.

    We have sifted through the noise to find who offers real relief for those in a tight spot. We prioritized lenders that utilize alternative data points, like your income history or banking relationships, to determine your creditworthiness.

    1. Max Cash
    2. Avant
    3. JetzLoan
    4. Acorn Finance
    5. NetCredit
    6. Upgrade

    How These Lenders Were Evaluated

    The selection process prioritized accessibility for borrowers with significant credit challenges. A 520 score is a tough climb. Our primary metric was whether the lender offers a path to approval without requiring a perfect history. We looked for services that prioritize speed and ease of application.

    We focused specifically on digital-first platforms that can process an application in under ten minutes. Beyond just the score, we assessed the variety of loan products available. Whether you need a small cash injection to cover an unexpected utility bill or a larger sum for home improvements, the lender must provide options.

    We also checked for features like “no credit impact” inquiries. This ensures you don’t sink your score further by performing “shotgunning,” which is the practice of applying to dozens of lenders at once in a desperate attempt to find a “yes.”

    Finally, we evaluated the transparency of their fee structures. For a borrower with a 520 score, unexpected origination fees or prepayment penalties can be the difference between staying afloat and falling deeper into a debt spiral. We sought out lenders that are upfront about their APRs before you commit to a formal application.

    Lender Name Loan Amounts Funding Speed Credit Impact for Quotes
    Max Cash $250 – $10,000+ Minutes No Obligation
    Avant See site See site See site
    JetzLoan $500 – $35,000 As little as 24 hours No impact
    Acorn Finance See site See site No impact
    NetCredit Up to $10,000 Same-day available No impact
    Upgrade Up to $50,000 Fast funding Won’t impact score

    The Best Lenders for Low Credit Scores

    1. Max Cash

    Max Cash – maxcash.com

    Max Cash acts as a bridge when the traditional banks turn their backs. They specialize in a wide variety of products, ranging from small personal loans to more substantial installment loans. If you are in a pinch, they aim to provide relief in minutes rather than days.

    This is particularly useful for “bridge financing,” where you need cash to cover a gap between two financial events, such as receiving a tax refund or a paycheck. It is a strong choice for those who need immediate liquidity to handle emergencies.

    They offer a massive range of loan amounts, starting as low as $250 and going well above $10,000. It is a versatile option for someone whose financial situation requires quick, flexible movement. Because the entry point is so low, it is an excellent tool for micro-needs that don’t justify a large, long-term debt commitment.

    Pros:

    • Extensive range of loan amounts from $250 to over $10,000.
    • Fast processing time measured in minutes.
    • No obligation for the initial personalized inquiry.

    Cons:

    • Focuses heavily on high-speed relief which can lead to higher interest costs.

    2. Avant

    Avant – avant.com

    Avant understands that a single number doesn’t tell your whole story. They aim to move people forward financially, offering tools that help you manage debt or handle unexpected household expenses. They are a structured option for those looking to build a more stable foundation.

    Unlike some lenders that only look at FICO, Avant’s underwriting may consider your relationship with your bank or your steady employment history. Whether you are looking for a credit card or a specific loan for home improvement, they offer various solutions.

    They are particularly useful for those who have moved slightly past the absolute bottom of the credit scale and need a reliable partner for long-term goals. If your score is climbing from 520 toward 600, Avant can be a partner in that upward trajectory rather than just a temporary fix.

    Pros:

    • Offers diverse products including credit cards and debt consolidation.
    • Designed to help users move forward financially.
    • Flexible solutions for different life stages.

    Cons:

    • Minimum credit score requirements may exclude the very lowest scores.

    3. JetzLoan

    JetzLoan – jetzloan.com

    If you are tired of waiting for a check to clear, JetzLoan is a breath of fresh air. They connect you with top lenders in a matter of minutes, making the comparison process incredibly efficient. It is a streamlined approach for the modern, busy borrower.

    Instead of you spending hours filling out dozens of different forms, JetzLoan’s marketplace model does the heavy lifting for you. They boast a high customer rating and have funded over 500,000 loans. With the potential to receive funds in as little as 24 hours, they are built for speed.

    The ability to check rates without a hard credit pull is a massive safety net for your score. This is critical because if you are already at a 520, even a few unnecessary hard inquiries can drop you into the high 400s, making you even less attractive to future lenders.

    Pros:

    • Extremely fast 24-hour funding potential.
    • No hard credit pull required to check rates.
    • High customer satisfaction rating.

    Cons:

    • The speed of funding depends heavily on the specific lender you are matched with.

    4. Acorn Finance

    Acorn Finance – acornfinance.com

    Acorn Finance is a specialized player, specifically targeting those who need financing for home improvement projects. They act as a marketplace, connecting you with various lenders. This is particularly helpful if you are trying to fix up a kitchen or a deck to increase home value.

    For many, home equity is their greatest asset, and using a loan to improve that asset is a strategic way to build long-term wealth even when credit is currently low. They offer a unique service where contractors can offer financing with zero dealer fees.

    This makes them a standout for larger, project-based needs. You can check personalized rates without any impact on your credit score, which is vital when your score is already shaky. For example, if you need a new roof, you can compare several specialized home improvement lenders through Acorn to see who offers the most competitive APR for your specific profile.

    Pros:

    • Specialized in home improvement contractor financing.
    • No credit score impact when checking rates.
    • Zero dealer fees for some contractor options.

    Cons:

    • More niche in focus, which may not suit general personal cash needs.

    5. NetCredit

    NetCredit – netcredit.com

    NetCredit markets itself as “Credit to the People,” emphasizing that you are more than just a number in a database. This philosophy is reflected in their use of advanced algorithms to look at a broader picture of your financial health beyond just the FICO score.

    They might look at your ability to pay through your banking activity, which is a game-changer for those with thin credit files or recent score dips. They offer personal loans and lines of credit with the potential for same-day funding.

    This is ideal for someone who needs to act immediately on a pressing financial obligation, like a sudden car repair that is preventing you from getting to work. They aim to provide a trustworthy and transparent experience for those often ignored by big banks, offering a more empathetic approach to the lending process.

    Pros:

    • Same-day funding is an available option.
    • Uses advanced algorithms to look beyond the credit score.
    • Checking eligibility does not affect your FICO score.

    Cons:

    • Loan amounts are capped at a relatively modest $10,000.

    6. Upgrade

    Upgrade is a heavy hitter in the personal loan space, catering to a massive customer base. They offer significant loan amounts, up to $50,000, which is excellent for major life events or consolidating high-interest debt. If you are carrying several high-interest credit card balances that are dragging your score down, this could be your exit strategy.

    Using an Upgrade loan to consolidate that debt into a single, lower-interest installment loan can be a powerful way to jumpstart your credit recovery. Their platform is designed for speed and convenience, allowing you to see rates in minutes.

    They also provide features like cash back on certain purchases, which can help you claw back some financial ground while you work on improving your credit standing. This dual-purpose approach—providing a loan while also offering tools to manage cash flow—makes them a comprehensive financial partner.

    Pros:

    • High loan limits up to $50,000.
    • Fast funding and quick rate checking.
    • Additional financial tools like cash-back checking accounts.

    Cons:

    • The focus on diverse financial products can be overwhelming if you only need a simple loan.

    The Costs of Low-Credit Borrowing

    When your score is in the 520 range, you must be prepared for the reality that borrowing will be more expensive than it is for someone with a 750 score. Interest rates are essentially a “risk premium” that lenders charge to compensate for the possibility that you might not pay them back. It is vital to understand the difference between a simple interest loan and a compound interest loan.

    Simple interest is calculated only on the principal amount. Compound interest is calculated on the principal plus any accumulated interest, which can cause your debt to snowball if you only make the minimum payments. Furthermore, you should always look for the “Total Cost of Loan” figure. A lender might advertise a monthly payment of $150, which sounds manageable, but if that loan is spread over 60 months, you might end up paying back $9,000 for a $5,000 loan.

    That is a $4,000 cost for the privilege of borrowing. Always ask: “How much total interest will I pay over the life of this loan?” This single question can save you thousands of dollars and prevent years of financial struggle.

    Strategies to Raise Your Score After Taking a Loan

    Taking a loan with a 520 score should be viewed as a tactical move to improve your financial standing, not just a way to cover a current bill. If you use a loan to consolidate debt, your goal is to use that breathing room to pay off the underlying balances and then leave those credit cards alone. If you pay off a credit card with a personal loan but then immediately run the credit card balance back up, you have effectively doubled your debt and will likely see your score plummet even further.

    To maximize the impact of your loan on your credit score, follow these three steps:

    • Automate your payments: A single missed payment can drop a score by 50-100 points. Set up autopay for at least the minimum amount to ensure you never miss a deadline.
    • Maintain a low utilization ratio: If the loan was used to pay down credit cards, keep those cards at less than 30% utilization. This is one of the fastest ways to see a score increase.
    • Avoid new debt for 6-12 months: Once you have stabilized your situation, resist the urge to open new lines of credit. Your score needs time to reflect the stability of your current repayment behavior.

    Navigating the Loan Process

    When you are working with a 520 score, every move counts. One of the biggest mistakes is applying for multiple loans at once. Each “hard pull” can shave points off your score, making your situation even more precarious. Always look for lenders that allow you to check rates with a “soft pull” or no impact on your credit score. This allows you to window shop for the best rates without the penalty of multiple inquiries.

    It is also vital to read the fine print regarding repayment terms. A quick loan might solve a problem today, but if the interest rates are astronomical, it could create a mountain of debt tomorrow. Always compare the total cost of the loan, not just the monthly payment, to ensure you are making a choice that actually helps you move forward.

    Look specifically for “prepayment penalties”—if you come into a windfall and want to pay the loan off early to save on interest, some lenders will charge you a fee for doing so. You want a lender that rewards you for being responsible, not one that penalizes you for being efficient.

  • Top 5 Best Personal Loans for a 550 Credit Score in 2026

    550 credit score personal loan

    Top 5 Best Personal Loans for a 550 Credit Score in 2026

    Last updated: 2026-10-16

    Trying to manage money with a 550 credit score often feels like walking through waist-deep mud. It is a tough spot to be in, especially when life throws a sudden curveball your way. An unexpected car repair, an urgent dental bill, or a surprise medical cost can arrive exactly when your bank account is at its lowest.

    Traditional banks might slam the door shut, treating a 550 score as an automatic disqualifier. However, several specialized lenders stay open for business. These companies use their own scoring models that look past your FICO number. They check your income stability, employment history, and even your banking relationships to see if you are a reliable borrower.

    Finding a lifeline requires more than just glancing at the interest rate. You have to weigh how fast you get the cash against the total cost of the debt. Some people need a low APR to keep long-term costs down. Others just need the money in their account within 24 hours to avoid an eviction notice or a late fee.

    This list highlights the most reliable options for anyone currently sitting in the fair to poor credit range. It provides a way to make sense of these high-stakes decisions when you need help quickly.

    1. LendingPoint
    2. FastLendGo
    3. Max Cash
    4. Avant
    5. Reprise

    How These Lenders Were Evaluated

    Evaluating lenders for low credit scores means looking past the marketing gloss. The main focus is accessibility and whether you can actually get funds despite a difficult credit history. It is not just about finding a company that says yes. It is about finding a company that offers a fair way to say yes.

    A lender might boast a high approval rate, but they aren’t a true lifeline if their terms include hidden service fees or predatory prepayment penalties. You need to know exactly what you are signing up for before you commit to the debt.

    Our selection process focused on lenders catering specifically to the 550 range. We looked at three main areas: accessibility, speed, and transparency. We checked how fast they deliver funds, how clear they are about loan amounts, and the variety of products they offer. Every entry was vetted to ensure they provide real pathways for immediate relief.

    We also tested the digital interfaces. If you are facing an emergency, you need to be able to complete the entire application from a smartphone while on the go. An interface that is hard to use can be a major roadblock when time is of the essence.

    Lender Name Loan Amounts Credit Requirements Funding Speed
    LendingPoint $1,000 – $36,500 Fair Credit Fast Funding
    FastLendGo $500 – $5,000+ Bad/Fair Credit Quick Access
    Max Cash $250 – $10,000+ Bad Credit In Minutes
    Avant See site 550 and above Fast Funding
    Reprise See site See site See site

    1. LendingPoint

    LendingPoint – lendingpoint.com

    LendingPoint helps people move from financial stress toward a bit more stability. They offer a wide range of loan amounts, making them a versatile choice. You might need a small amount for a medical bill or a much larger sum to consolidate debt.

    If you are carrying $15,000 in high-interest credit card debt, your monthly payments can start to spiral out of control. A single consolidation loan from LendingPoint can simplify everything into one predictable monthly payment. It is a way to stop chasing multiple due dates every month.

    This lender works well for people tackling specific burdens like home improvements or debt. Their digital experience is streamlined to respect your urgency. You can upload documents and get a decision in minutes, which is vital when you are managing a very tight budget.

    Pros:

    • High maximum loan ceiling up to $36,500.
    • No impact on credit score when checking rates.
    • Versatile loan purposes including wedding and travel.

    Cons:

    • May have stricter requirements than specialized bad credit lenders.

    2. FastLendGo

    FastLendGo – fastlendgo.com

    FastLendGo is built for the person who needs cash yesterday. They focus on quick access for needs like auto repairs or dental financing. If your car’s alternator fails and you need it fixed by Monday to keep your job, their specialized products are designed for that exact situation.

    They occupy the space between traditional banking and high-interest payday loans by providing structured personal loans. This gives you more stability than a short-term cash advance but more speed than a standard bank loan.

    Whether you need a $500 boost or a $5,000 loan, they offer various tiers. This flexibility matters when your score is in that tricky 550 zone. Instead of being forced into a massive loan you cannot afford, you can opt for a smaller amount that fits your immediate crisis.

    Pros:

    • Covers a wide range of specific emergencies like roof or motorcycle loans.
    • Offers very small loan amounts for immediate needs.
    • Provides options for high-income individuals and first-time borrowers.

    Cons:

    • The variety of products can be overwhelming for some.

    3. Max Cash

    Max Cash – maxcash.com

    Max Cash acts as a matching service to find you relief. For those struggling with a 550 score, they offer a way to find personalized lender matches. Their system connects you with what you actually need, which saves you from searching through dozens of different websites.

    Instead of a one-size-fits-all approach, they use an algorithm to find the lender most likely to approve your specific profile. It is about efficiency rather than just throwing a net into the water and hoping something sticks.

    They specialize in highly accessible amounts, starting as low as $250. This is perfect for micro-emergencies where a large loan would be overkill. If you have a $300 utility bill, taking out a $3,000 loan would be a mistake. Max Cash lets you solve the small problem without the heavy burden of excessive interest.

    Pros:

    • Extremely low entry point for loan amounts.
    • Fast inquiry process with no obligation.
    • Handles a wide variety of credit situations.

    Cons:

    • Focus on small amounts may not suit major debt restructuring.

    4. Avant

    Avant – avant.com

    Avant is a major player for anyone looking to move forward financially. They are known for considering applicants with scores as low as 550. This makes them a vital option if you have been told no by the big-name traditional banks.

    Unlike some lenders that only care about your FICO score, Avant looks at a broader view of your financial health. This can be a game-changer for people who have had recent setbacks but still maintain a steady income.

    The lender is geared toward long-term solutions like debt consolidation or home improvements. If you apply before their afternoon cutoff, you might see funds hit your account remarkably quickly. Their platform is designed for the modern consumer who wants to manage everything from a mobile app.

    Pros:

    • Specifically caters to the 550 credit score demographic.
    • Fast funding capabilities for approved applicants.
    • Offers both credit cards and loans for different needs.

    Cons:

    • Approval is heavily dependent on specific timing and criteria.

    5. Reprise

    Reprise – reprise.com

    Reprise operates in a different sphere, focusing on high-tech solutions and AI-driven tools. It is not a traditional consumer personal loan lender like the others. Instead, it represents the newer side of financial technology and data management.

    They are best suited for businesses or tech-forward entities looking for advanced demo creation and data injection. It is a specialized tool for those who need to present complex data in an interactive way, rather than a standard consumer seeking quick cash.

    For a fintech startup looking to demonstrate how a loan application process works to potential investors, Reprise offers the tools to build that interactive experience. It is about the technology behind the scenes rather than the consumer at the counter.

    Pros:

    • Highly advanced AI toolset for demo creation.
    • Efficient data injection and presentation capabilities.
    • Allows for easy sharing of product tours.

    Cons:

    • Not a traditional personal loan provider for individual consumers.

    Understanding the Cost of Borrowing: APR vs. Monthly Payment

    When you are in a financial bind, it is easy to fall into the trap of shopping only for the lowest monthly payment. You might see two loan offers: one with a $50 monthly payment and another with a $75 monthly payment. The $50 option looks like the winner because it leaves more money in your pocket today.

    However, this is a dangerous way to evaluate debt. The true cost is found in the Annual Percentage Rate (APR). A lender might offer a low monthly payment by stretching the term of the loan out over seven years. While your monthly obligation is lower, you could end up paying double or triple the amount you originally borrowed due to the interest.

    Always ask: “What is the total amount I will have paid back by the time this loan is finished?” If that number is significantly higher than the principal, you are paying a massive premium for the convenience of a lower monthly payment.

    The Impact of Hard vs. Soft Credit Inquiries

    A critical piece of knowledge for anyone with a 550 score is understanding how the application process affects your rating. There are two types of inquiries: soft pulls and hard pulls. A soft pull occurs when a lender checks your credit to see if you are pre-qualified. This happens when you use “check your rate” features.

    These inquiries do not show up on your credit report to other lenders and they do not lower your score. They are essentially a way to window shop without any penalty.

    A hard pull occurs when you officially submit an application for a loan or credit card. This signals to the credit bureaus that you are actively seeking new debt, which is seen as a risk factor. Each hard pull can cause a small, temporary dip in your score. If you are trying to repair your credit, you want to minimize these pulls.

    How to Choose and Avoiding Pitfalls

    Choosing a lender is a bit like picking a pair of shoes; if they don’t fit right, you’re going to have a painful journey. Always look at the total cost of the loan, not just the monthly payment. A low monthly payment might hide a massive interest rate that will drain your wallet over time.

    You should always request a truth-in-lending disclosure. This is a legal requirement that clearly outlines the total finance charge and the total amount you will eventually pay back. It takes the guesswork out of the equation.

    One of the biggest mistakes people make is applying for multiple loans all at once. This creates a “shotgun” effect where several hard inquiries hit your report in a short window. This makes you look desperate to creditors and can further tank your score. Instead, pick one or two lenders that match your specific need and focus there.

    Finally, read the fine print. Ensure you understand the repayment terms and check for prepayment penalties. Some lenders charge you a fee if you try to pay the loan off early. You don’t want to be stuck in a high-interest trap when you are finally ready to be debt-free. Use these lenders as a tool for recovery, but use them wisely.

    fastlendgo.com

  • Get a 100k Personal Loan Today

    100k personal loan

    Get a 100k Personal Loan Today

    Evaluating the Cost of a $100,000 Unsecured Loan

    Walking into a bank to ask for $100,000 feels like stepping into a high-stakes poker game. You might walk away with a winning hand, or you might find the dealer holding all the cards. The interest rates you eventually secure depend heavily on your credit profile. It acts as the ultimate gatekeeper to affordable capital.

    If your credit score is pristine, you might see APRs starting as low as 7%. This is the gold standard. For those with less-than-stellar credit, however, the numbers can quickly spiral. It is not uncommon to see rates climb toward 36% when lenders decide the risk of default is too high to ignore.

    Think of your credit score as a weather forecast for your wallet. A high score brings sunshine and low rates, while a lower score brings a storm of high interest. This gap can mean the difference between a manageable monthly bill and a financial nightmare that keeps you up at night.

    When comparing lenders, you’ll notice a massive divide. Traditional banks often demand a history of stability, whereas online lenders might offer speed at the cost of higher rates. Credit unions frequently provide a middle ground, offering competitive rates that feel a bit more human and less like a cold, calculated algorithm.

    The Monthly Burden and Term Lengths

    Time is a double-edged sword when you are staring down a $100,000 principal. Choosing a longer term might make your monthly payments look much more appetizing on paper. That extra time is exactly what allows interest to compound and eat away at your wealth like a slow-moving tide.

    Let’s look at the math. If you snag a rate around 9.49% APR, your monthly commitment remains relatively stable. But if you’re forced into a 36% APR territory, the numbers become quite staggering. It’s vital to run these numbers through a calculator before signing anything binding.

    Consider this breakdown for a $100,000 loan to see how the math shifts:

    Estimated APR Term Length Monthly Payment
    9.49% 3 Years $3,215
    9.49% 5 Years $2,100
    18% 5 Years $2,566
    36% 5 Years $3,450

    As the table shows, the difference between a 9.49% rate and a 36% rate over five years is nearly $900 every single month. That is money that could have gone toward a retirement fund or a down payment on a home. It is a steep price to pay for a high-interest loan.

    The Hidden Weight of Total Repayment

    The sticker price of a loan is rarely the actual price you pay. You must account for invisible costs, such as origination fees. These are often deducted from your principal upfront. This means you might receive less than the $100,000 you actually requested from the lender.

    If you are looking to find the best terms, you might want to explore specialized services like https://fastlendgo.com to see how different structures impact your bottom line. Always look closely at the fine print regarding any prepayment penalties. These can prevent you from paying the debt off early.

    Total cost of borrowing is the most important metric. A $100,000 loan at 10% over five years might cost you roughly $26,000 in total interest. That is a significant chunk of change. If the rate jumps to 25%, you are suddenly looking at an extra $40,000 in interest alone.

    Always ask your lender: “What is the total amount I will have paid by the time this is finished?” It is a simple question that provides a sobering reality check. Don’t let the monthly payment be the only number that guides your decision-making process.

    Comparing High-Limit Lenders and Loan Caps

    Chasing a six-figure sum is a different beast entirely compared to asking for a small quick fix. When you move into the $100,000 territory, you aren’t just a customer. You are a high-value asset. Lenders look at your profile with a magnifying glass, scrutinizing every detail of your financial history to decide if you are worth the risk.

    SoFi stands out in this arena. They are known for offering unsecured personal loans that can reach up to $100,000. This makes them a go-to option for people looking to consolidate massive amounts of debt or fund significant life changes without putting their home on the line.

    However, not every lender is ready to play in the big leagues. You will often find a middle ground where the stakes are lower but the accessibility is higher. These lenders act as the reliable workhorses of the financial industry, providing the necessary fuel for those who don’t quite need a massive windfall.

    Axos Bank is a prime example of this mid-range tier. They typically cater to borrowers looking for sums between $7,000 and $50,000. While they might not hand you $100,000 on a silver platter, their terms are often structured to be incredibly predictable and user-friendly for the average consumer.

    The Spectrum of Collateral and Risk

    One of the biggest forks in the road is deciding between unsecured and secured options. An unsecured loan is like a handshake deal backed by your reputation. You don’t have to put up your car or your house as collateral. This means your assets are safe if things go sideways. It is pure trust, albeit expensive trust.

    Secured loans, on the other hand, require you to put something on the table. Usually, this is an asset like a vehicle or a savings account. If you miss payments, the lender can take that asset. It is a safety net for the bank, which often results in much lower interest rates for the borrower.

    If you are looking for speed, the modern digital landscape is a lifesaver. Many lenders now offer fast online prequalification. This process uses a “soft credit pull,” which is like a window shopper looking at prices without actually buying anything. It won’t ding your credit score, allowing you to test the waters safely.

    You can peek at your potential terms without the fear of a damaged score. This is a game-changer for anyone who wants to shop around for the best deal. You can compare multiple offers from various institutions before ever committing to a hard inquiry that could impact your standing.

    The following table illustrates how different loan structures and amounts can impact your borrowing experience:

    Loan Type Maximum Amount Typical Term
    High-Limit Unsecured $100,000 Up to 7 Years
    Mid-Range Personal $50,000 3 to 6 Years
    Small Personal Loan $7,000 2 to 5 Years
    Secured Loan Variable Variable

    Flexibility in Repayment and Timing

    When you sign on the dotted line, the clock starts ticking immediately. Most lenders offer a variety of repayment terms, typically ranging from 3 to 6 years. Choosing a shorter term is like running a sprint. You’ll pay less in interest, but your monthly bills will be much steeper.

    Taking the longer route is more like a marathon. It keeps your monthly cash flow comfortable, giving you more breathing room for other expenses. You must remain vigilant, though. The longer you stretch that debt out, the more the total interest accumulates, potentially costing you thousands in the long run.

    It is vital to find the “sweet spot” where the monthly payment doesn’t break the bank, but the total interest doesn’t drain your future savings. Don’t just settle for the first offer that lands in your inbox. Take your time, run the math, and ensure the terms align with your long-term goals.

    Strategic Use Cases for Large-Scale Personal Financing

    Mastering Debt Consolidation

    Imagine waking up to a mountain of high-interest credit card statements every month. It feels like trying to swim against a heavy tide of compounding interest. A $100,000 loan can act as a life raft, allowing you to sweep up those various expensive balances into one single, manageable payment. This shift can dramatically improve your monthly cash flow.

    By moving high-interest debt into a lower-interest unsecured loan, you are essentially stopping the bleeding. Instead of fighting multiple battles with different due dates, you focus on one. Many borrowers find that rates as low as 9.49% APR can make a massive difference compared to the 20% or 30% interest rates often found on revolving credit cards.

    This strategy is not just about convenience; it is a calculated move to save money. When you consolidate, you are often trading “expensive” debt for “cheaper” debt. This can significantly lower the total amount you pay over the life of the loan, provided you resist the urge to run up those credit card balances again.

    However, success requires discipline. It is easy to clear your cards and feel like you have a fresh start, only to fall back into old habits. Think of the loan as a tool to clean the slate, not a license to spend more. If you handle it right, you’ll find yourself standing on much firmer financial ground.

    Funding Major Life Transitions

    Life has a way of throwing curveballs that require immediate, heavy-duty capital. A sudden medical emergency can feel like a financial gut punch, potentially depleting your entire savings in a heartbeat. In these moments, a large personal loan provides the liquidity needed to cover costs without sacrificing your long-term security or your home.

    Home renovations are another classic reason to seek out a substantial sum. Perhaps you want to remodel a kitchen or add a second story to increase your property’s value. Using $100,000 for these upgrades can be a smart investment, as the equity gained in your home often outweighs the cost of the financing itself.
    Some people use this capital to bridge the gap during a career transition or to fund a significant life event like a wedding or a move. It is essentially a way to smooth out the jagged edges of life’s most expensive moments. It provides a sense of stability when everything else feels like it is in flux.
    When you use a lump sum for these purposes, you are essentially pre-funding your future needs. Instead of paying small amounts as they arise, you have the firepower to tackle the entire project or bill at once. This can often lead to better pricing from contractors or more negotiating power with service providers.

    Capital Investments and Fixed Rates

    For the more entrepreneurial mind, a $100,000 windfall can serve as seed money for a side business or a significant capital investment. Whether it is purchasing equipment, upgrading technology, or investing in a small franchise, having a large lump sum allows you to strike while the iron is hot. It turns a “maybe” into a “now.”

    One of the most powerful features of these large loans is the ability to lock in a fixed rate. This is a massive advantage for your mental peace of mind. Unlike variable rates that can swing wildly, a fixed rate ensures your monthly payment stays exactly the same from the first month to the last.

    This predictability is the cornerstone of a healthy budget. You won’t wake up one morning to find your interest rate has spiked, eating into your grocery money. It allows you to plan your life with confidence, knowing exactly what your financial obligations will be for the next several years of your life.

    When you manage a large sum through a fixed-rate structure, you are effectively buying certainty. In an unpredictable economy, that certainty is worth its weight in gold. It turns a potentially volatile financial situation into a predictable, scheduled part of your monthly household management.

    The Math of Efficiency

    Is it better to take one giant loan or several smaller ones? Many people assume that breaking things up is easier, but the math often tells a different story. Multiple loans mean multiple origination fees, multiple interest rates, and a cluttered dashboard of due dates that can lead to accidental late fees.

    Taking one large $100,000 loan can be far more cost-effective than taking five $20,000 loans. By consolidating your needs into a single request, you often secure a better overall interest rate and significantly reduce the administrative headache. It is about streamlining your financial life to maximize every dollar you earn.

    Consider the following comparison of how different borrowing structures might impact your total costs:

    Strategy Complexity Total Interest Risk Management Effort
    Single $100,000 Loan Low Lower (due to lower APR) Minimal
    Multiple $20,000 Loans High Higher (compounding effects) Significant
    Small Revolving Credit Very High Extremely High Constant

    Ultimately, the goal is to minimize the “leakage” of your wealth. Every dollar spent on extra interest or late fees is a dollar that isn’t working for you in a savings account or a retirement fund. Choosing the most efficient loan structure is a key step in building real, lasting wealth.

    The Application Roadmap and Qualification Requirements

    The Path from Inquiry to Funding

    Embarking on a $100,000 loan journey is not a sprint; it is a carefully choreographed dance. You should start by checking your credit score to see where you stand. This initial step ensures you aren’t walking into a room blindfolded, unaware of the interest rates waiting on the other side of the door.

    Once you have a clear picture of your credit, the real work begins. You will need to find a lender that fits your specific needs and profile. After you submit your formal application, the lender will dive into your financial history. This phase can take anywhere from a few days to a few weeks depending on the institution.

    After the lender gives you the green light, you will sign the final paperwork to lock in your terms. Finally, the funds are disbursed into your bank account. It is a whirlwind process, but following the steps in order helps ensure you don’t trip over any unexpected financial hurdles along the way.

    To keep things organized, think of the roadmap in these general stages:

    • Credit Check: Assessing your current standing and score.
    • Prequalification: Getting a “soft” estimate of your terms.
    • Formal Application: Submitting the official request for $100,000.
    • Underwriting: The lender verifies all your provided information.
    • Approval and Funding: Signing the contract and receiving cash.

    The Math Before the Money

    Before you ever click that “apply” button, you must do the math. It is easy to get swept up in the idea of a $100,000 windfall, but the monthly reality can be quite sobering. You need to know exactly what your monthly obligation will look like to ensure your budget can handle the weight.

    Use a calculator to play with different scenarios. For instance, if you borrow $100,000 at a 10% interest rate over five years, your monthly payment will be significant. If you cannot comfortably afford that number, you might need to adjust your loan amount or extend the repayment term to find a sweet spot.

    Ignoring the monthly cost is like driving a car without checking the fuel gauge. You might feel great while you’re moving, but a sudden realization that you can’t afford the next tank can leave you stranded on the side of the road. Always aim for a payment that fits seamlessly into your lifestyle.

    Consider these hypothetical monthly payment estimates for a $100,000 loan:

    Interest Rate (APR) Term Length Estimated Monthly Payment
    7% 5 Years ~$1,980
    12% 5 Years ~$2,224
    18% 5 Years ~$2,566

    Verifying Your Financial Identity

    Lenders aren’t just handing out large sums of cash on a handshake. They need to be absolutely certain that you are who you say you are and that you actually earn what you claim. This means you’ll need to gather a mountain of documentation to prove your employment and income status.

    Typically, you will need to provide recent pay stubs, W-2 forms, or tax returns. If you are self-employed, the requirements get a bit more rigorous. You might need to present several months of bank statements to prove that the money flowing into your accounts is consistent and reliable.

    Don’t forget the basics like government-issued ID and proof of residence. If your paperwork is a mess, the whole process can grind to a screeching halt. Think of your documentation as your financial resume; it needs to be clean, organized, and ready for immediate inspection at a moment’s notice.

    The Credit Score and Rate Connection

    Your credit score acts as a VIP pass in the world of lending. It dictates which “tier” of interest rates you will fall into. A high score might get you a rate as low as 9.49% APR, while a lower score could see you paying much more, potentially increasing your total cost by thousands.

    Lenders view credit scores as a measure of risk. The higher your score, the less risk they perceive, which allows them to offer you better terms. Conversely, if your score is in the lower ranges, you might find that many lenders simply won’t offer you a sum as large as $100,000.

    It is vital to understand that even a small difference in your APR can result in massive savings over the life of a long-term loan. A 2% difference might seem minor today, but it adds up to a heavy price tag over several years of repayment.

    Smart Prequalification Tactics

    One of the best ways to shop around is through the prequalification process. This is a “soft” credit inquiry, which is a crucial distinction. A soft inquiry allows a lender to check your credit without leaving a permanent mark on your report, protecting your score from unnecessary damage.

    You should use this opportunity to cast a wide net. Many online lenders offer fast, online prequalification that gives you a glimpse of your potential interest rate and loan amount. It is a low-stakes way to compare different offers before you commit to a formal application.

    Once you find an offer that looks promising, you then move to the “hard” inquiry stage. This is the formal application that does impact your credit score. By using prequalification first, you ensure that you only trigger those hard inquiries when you are serious about a specific lender’s terms.

    Financial Math and Monthly Payment Projections

    The Power of the Personal Loan Calculator

    Before you sign on the dotted line, you must sit down with a personal loan calculator. It is the best way to strip away the mystery of high-interest debt. By plugging in different numbers, you can see exactly how much of your hard-earned paycheck disappears every single month.

    Think of a calculator as a crystal ball for your bank account. It allows you to simulate various scenarios without any real-world consequences. You can test how a $100,000 loan behaves under different interest rates, from a low 9.49% APR to much higher, more expensive tiers.

    Many people find that the math tells a very different story than their initial expectations. A loan that looks manageable at first glance can quickly become a heavy anchor. Using these tools helps you avoid the “sticker shock” that often occurs when the first major payment is due.

    Comparing Loan Magnitudes

    The jump from a $30,000 loan to a $100,000 loan is not just a matter of adding zeros; it is a massive shift in your financial landscape. While a $30,000 loan might feel like a manageable bump in the road, a $100,000 loan is more like a mountain climb.

    When you borrow $30,000, your monthly obligations stay relatively contained. However, when you scale up to $100,000, the interest accumulates at a much faster pace. You are essentially paying for the privilege of having a much larger pile of cash sitting in your hands today.

    Consider the following comparison to see the sheer weight of the difference in principal amounts:

    Scenario Loan Amount Interest Rate Estimated Monthly Payment
    Small Scale $30,000 10% ~$633
    Large Scale $100,000 10% ~$2,124

    Fixed vs. Variable Interest Rates

    Choosing between a fixed-rate and a variable-rate loan is like choosing between a steady walk and a roller coaster. A fixed rate offers peace of mind because your monthly payment stays exactly the same for the entire life of the loan. It is a predictable, stable path.

    Variable rates, on the other hand, can be a double-edged sword. They might start out lower than fixed rates, which feels like a win for your wallet. However, if market interest rates climb, your monthly payment can skyrocket without any warning from your lender.

    If you are planning to hold a $100,000 loan for several years, predictability is often worth the extra cost. You do not want to wake up three years from now to find that your interest rate has jumped, turning your budget into a chaotic mess of unexpected expenses.

    The Tug-of-War Between Duration and Cost

    Loan duration is a balancing act that pits your monthly cash flow against the total cost of the debt. A longer term, such as six years, makes your monthly payment much smaller and easier to digest. This provides much-needed breathing room in your monthly budget.

    However, there is a catch: time is expensive. The longer you take to pay back the loan, the more interest you will pay in total. You might save $200 every month, but you could end up paying thousands of dollars more to the bank over the long haul.

    It is vital to find your personal “sweet spot.” You want a term long enough to keep your monthly payments comfortable, but short enough that you aren’t throwing away a fortune in interest payments. Finding this equilibrium is the key to long-term financial health.

    The Impact of Early Repayment

    Life happens, and sometimes you might find yourself with extra cash to throw at your debt. This is where early repayment comes into play. Paying down your principal faster can save you a mountain of money in interest over the life of the loan.

    Before you get too excited, you must check for prepayment penalties. Some lenders include clauses that charge you a fee if you pay the loan off too early. They want to ensure they collect the interest they originally projected from you.

    Always read the fine print in your contract. If there are no penalties, making even an extra $50 payment each month can shave months off your repayment schedule. It is a small sacrifice today that yields massive rewards for your future self.